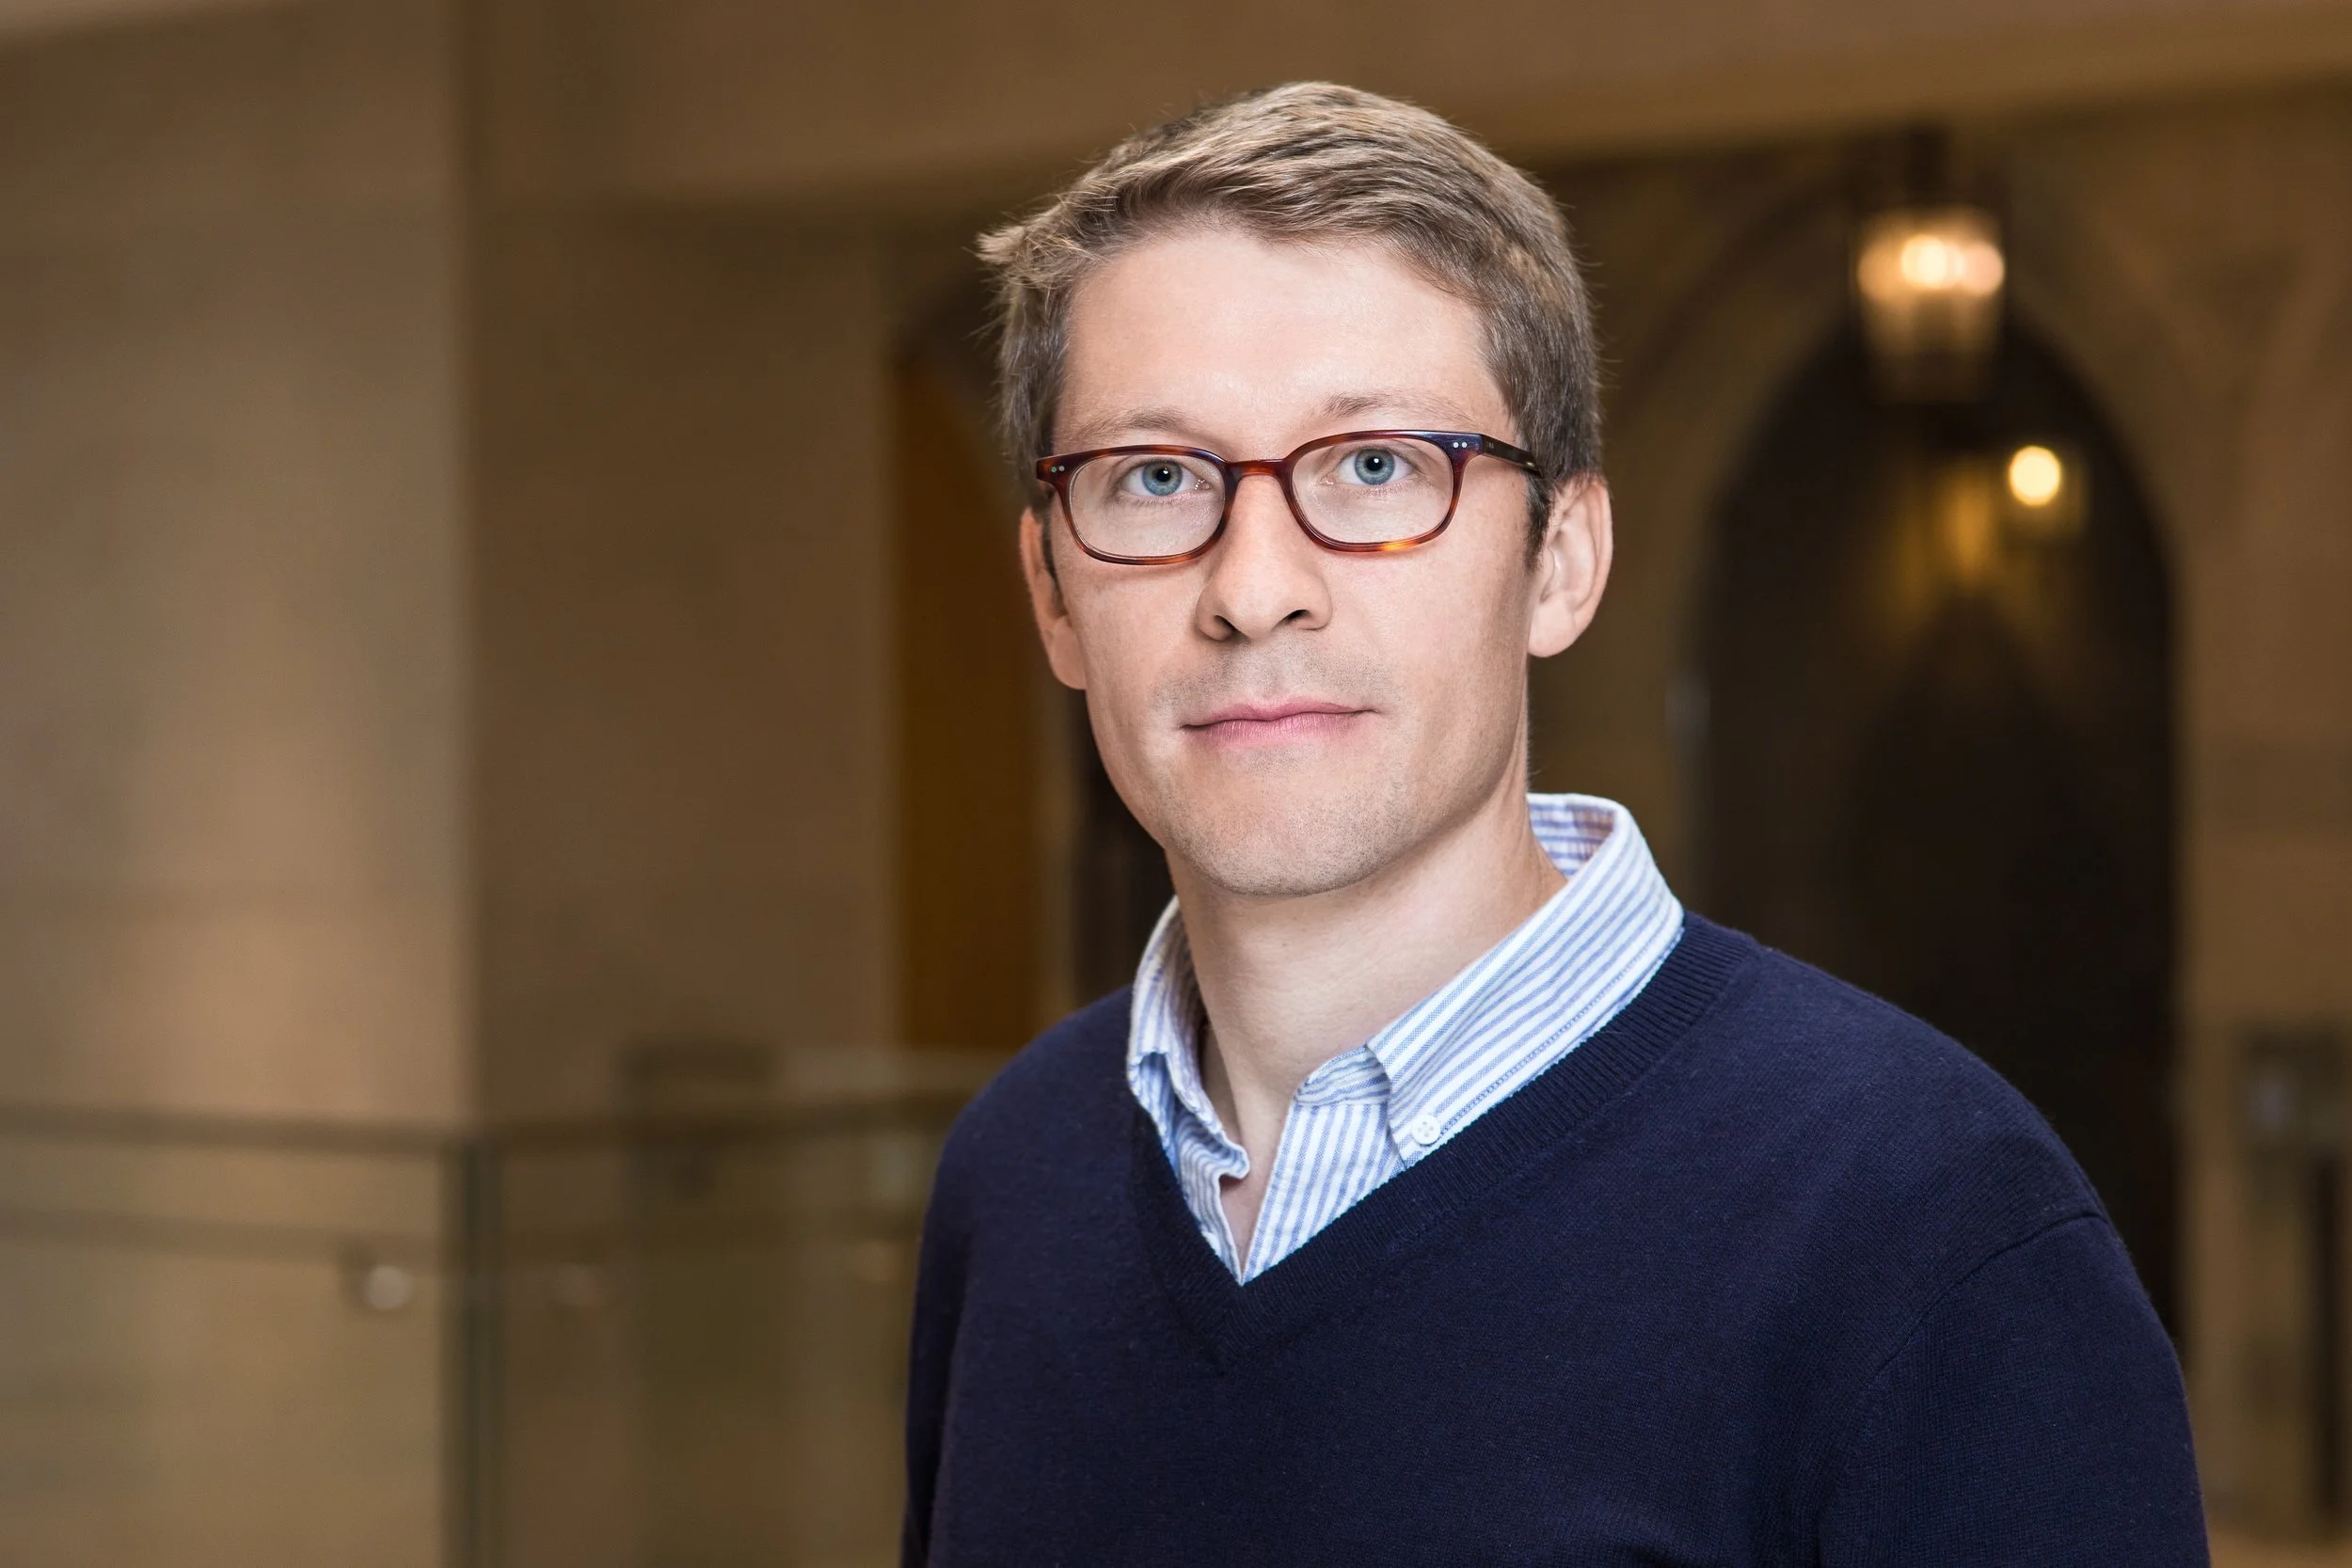
Qwen Zidar is the Co-author of The Everywhere Millionaire and Professor of Economics and Public Affairs at Princeton University. Zidar earned a Ph.D. in Economics from the University of California, Berkeley, and a B.A. from Dartmouth College. He lives in Princeton, New Jersey, with his wife and three children.
What happens when a small group of exceptionally wealthy people holds a growing share of a country’s income and wealth? And what can economics tell us about the forces behind that concentration?
In this episode, we are joined by Owen Zidar, professor of economics and public affairs at Princeton University and coauthor of the forthcoming book The Everywhere Millionaire. We explore the rise of the millionaire class, how tax policy shapes inequality, and why the geography of wealth matters when trying to understand the economic landscape.
We also discuss the role of entrepreneurship, industry-specific knowledge, and concentrated ownership in building wealth. Owen shares insights from extensive Treasury data, interviews with business owners, and research into the paths taken by millions of entrepreneurs. The conversation examines why access to capital may be less important than practical experience, how private equity can help or hurt business owners, and how local business consolidation can affect both consumers and workers.
Finally, we explore the influence of “everywhere millionaires” on public policy, the impact of interest rates on wealth valuations, and possible ways to expand access to entrepreneurial opportunities without undermining economic growth.
Key Points From This Episode:
(0:01:01) Why the typical wealthy American is more likely to be a business owner than a celebrity or Wall Street executive.
(0:01:58) How “everywhere millionaires” can provide a roadmap for building wealth and understanding inequality.
(0:03:19) The rise of entrepreneurial income among the top 0.1% over the past several decades.
(0:04:34) Why the inequality debate often overlooks wealth generated by private businesses.
(0:05:34) Why the typical millionaire is more likely to be found on Main Street than Wall Street.
(0:06:18) The ordinary—and sometimes unusual—industries that produce substantial wealth.
(0:07:47) Why building wealth through business ownership often takes decades.
(0:08:40) The role of concentrated ownership and the risks involved in becoming wealthy through entrepreneurship.
(0:09:37) How failed businesses can still provide valuable human capital and career opportunities.
(0:10:32) Which early-career paths may put people on track to become business owners.
(0:12:00) Why domain expertise and industry experience can matter more than access to capital.
(0:15:11) The Treasury data, tax records, research papers, interviews, and other sources behind The Everywhere Millionaire.
(0:16:40) How lower interest rates, tax cuts, deregulation, and globalization contributed to wealth accumulation.
(0:18:04) What the data suggests about academic performance, risk-taking, and entrepreneurial success.
(0:19:38) Why attending an elite university is not necessarily a prerequisite for becoming wealthy through business ownership.
(0:20:43) The importance of early labor-market experience and practical knowledge in entrepreneurship.
(0:22:03) The factors that help certain places foster upward mobility.
(0:30:00) How family businesses, inheritance, and succession can shape the distribution of wealth.
(0:37:52) How business owners can successfully exit their companies, including the role of seller financing.
(0:38:55) The potential benefits and drawbacks of private equity for business owners.
(0:41:19) How “stealth consolidation” can allow businesses to gain local market power without attracting regulatory scrutiny.
(0:42:41) The possible relationship between product-market power and labor-market power.
(0:44:19) Whether the United States is experiencing a new Gilded Age—and how today’s wealthy differ from those of the past.
(0:45:53) Why local business owners can have significant economic and political influence in their communities.
(0:48:33) How interest rates affect the value of private businesses and other assets.
(0:49:35) How apprenticeships and alternative career paths could expand access to financial success.
(0:50:27) What aspiring entrepreneurs can do to reduce risk and improve their chances of success.
(0:51:31) Potential approaches to reducing inequality while preserving incentives for business growth and investment.
(0:53:34) Owen’s reflections on family, personal fulfillment, and how he defines success.
Read The Transcript:
Ben Felix: Welcome to episode 428 of the Rational Reminder Podcast. I'm Ben Felix, Chief Investment Officer at PWL Capital.
Cameron Passmore: And I'm Cameron Passmore, Chief Executive Officer at PWL Capital. Today, Ben, we were joined by Owen Zidar, Professor of Economics, financial researcher and coauthor of the forthcoming book, The Everywhere Millionaire.
Ben Felix: Owen is a Professor of Economics and Public Affairs at Princeton. In the episode, we talk about the unglamorous industries behind most fortunes, what the inequality debate misses, and how the rich spend their money and their time. Super interesting.
Cameron Passmore: Super interesting. As always, stick around to the end to hear our thoughts about the conversation with Owen, but for now, let's get into the episode.
Ben Felix: Owen Zidar, welcome to the Rational Reminder Podcast.
Owen Zidar: Thanks for having me.
Ben Felix: Owen, what's wrong with the common perception of what it means to be wealthy?
Owen Zidar: Most people think that the way you get rich is to be like Elon Musk or Jamie Dimon or Taylor Swift. When you look in the data, that's just not actually at all who the typical rich person is in America. They are often ordinary business owners who've gotten extraordinarily rich running unglamorous private businesses.
So I have three young kids, and so I read a lot of kids' books. And we've half-jokingly talked about writing the ABCs of getting rich for the children's market. It's like A, for auto dealer, B, for beverage distributor, and C, for contractor.
They're pretty mundane businesses, but when you have the opportunity like us to work with the treasury and see the full map of wealth in America, it's just very different because people don't answer surveys. Unless you have investigative journalists or a celebrity following, you're just not going to see the vast majority of private companies that don't have to file quarterly to investors.
Ben Felix: Can you talk about why that's important for people to understand?
Owen Zidar: Yes. There are two key reasons. One is if you want to get rich yourself, I think these everywhere millionaires provide a roadmap for success in America.
And the second is if you want to understand the economy and influence, these folks are really central characters in the saga of rising inequality in America.
Ben Felix: So interesting. It makes me think about, I listened to a podcast a while ago with Mike Rowe. Do you remember the show Dirty Jobs?
Owen Zidar: No, but I know the title, but I think that's in the right vicinity.
Ben Felix: He did the show where he would go and kind of spend a day with people that did really dirty, like people cleaning sewers and stuff like that. And he talked about how a ton of those people, you would never know from watching the show, but a ton of those people were very wealthy because they own these types of businesses.
Owen Zidar: That's spot on. It's funny. Our neighbor is like talking about turning this into a documentary and he puts the first clip together.
And one of the things he shows of going from like the Great Gatsby, Leonardo DiCaprio, and a nice scene from the show Billions, and he goes right to porta potties. And it's just like this guy who owns a hundred porta potties. And, you know, think about all the big events, like all the races.
Toronto has a big marathon. You name the thing and someone needs to get porta potties there and clean them. And it turns out that's a pretty good business if you have it at some scale.
Cameron Passmore: Sure is. How has the source of income at the very top changed over the past century?
Owen Zidar: It's quite interesting to watch the rise of entrepreneurial income from private business. If you look at top 0.1% of income, I'll give you a few numbers. So in 1960, 17% of that income came from entrepreneurial income from business owners, and almost twice that came from wages.
If you go to 2022, 43% came from private business and only 35% came from wages. And so you've seen this big rise in the share of income, especially at the top from private business. And so that's another reason why I think this is quite important.
One way to quantify that is to think about one of the most famous graphs in economics. So Thomas Piketty and Emmanuel Saez had this famous U-shape top 1% graph, where over the 20th century, they plot the share of income going to the top 1%. And if you do that same plot, but hold fixed the contribution of private business and mid 1980s, you only get half the rise in the top 1%.
And so that's another way of accounting for how big this is. More than half of the rise of that famous top 1% share.
Ben Felix: Why is the common discourse about inequality incomplete?
Owen Zidar: I mean, some of it is we just have had bad data. If you can't measure it, it's just not going to be very salient, but that's completely at odds with what people see if you start to think about it. So go to any nice golf resort or a nice lake or a nice mountain town and ask who owns the big houses and just go and ask them, what do you do?
How did you make your money? And it's a lot of mundane things, like this guy owns seven Jiffy Lubes or this guy distributes toilet paper for regional restaurants, or this guy sells door handles. And it's some of those dirty jobs that you talked about that turns out to be what you see in the data.
So some of it was just, we had this really unique opportunity to get a decade of work with the treasury where we could see every private business in America. And that's what really shined the light on this hidden world of everywhere millionaires.
Owen Zidar: It's definitely more Main Street. So we added up all top 0.1% income of these private business owners and only about 20% comes from finance and real estate. And the majority come from every other industry, construction, healthcare, you name it.
We're mostly a service economy. And another interesting thing is that it's in every town. So if you plot population, it does a pretty good job of predicting where you'll have a lot of the profits throughout the country.
Whereas if you think it's just Wall Street, everything's happening in California, New York and Silicon Valley and New York, and it's just not the case empirically.
Ben Felix: Can you talk more about the industries that typically make the Main Street millionaires?
Owen Zidar: I told you the ABCs. We tabulated by four-digit sector, all of the top industries, and there are some white-collar ones and some blue-collar ones. So the white-collar ones are like law firms.
There are a ton of lawyers in America. Collectively, they make more than a hundred billion dollars in top-owned firms and dentists and doctors, you see that type. But then there's a lot of really niche things like miscellaneous parts manufacturing, auto dealers show up pretty high in there, construction, architects, a lot of skilled service providers.
It's a range of really small things that you don't really see. But when you look at other data sets that we bought, so we bought private jet data, we bought private yacht data, and you see tons of interesting people coming, people who own convenience stores. So there's this one guy that we talk about in the book, Beaver Aplin, who owns a chain of convenience stores called Buc-ee's in the South, kind of in rural Texas.
And so if you haven't been to Texas or Louisiana, you might not have heard about this guy, but these things are like football field sized. Everything's bigger in Texas. I went to high school in Texas.
It's very much true of these convenience stores. There's people who make millions selling Buc-ee's merchandise like secondhand online. And that's just not the image that normally comes to mind when you think about who's really rich.
Owen Zidar: One thing that emerges from the data is that it's typically a white male who's in their 60s. And one of the reasons why is it takes decades to earn that much money.
The Silicon Valley, going to move fast and break things, make money, make some app and get rich insanely fast is just not the model. That's not the typical business owner. It often takes a lot of rolling up your sleeves, decades of grinding it out, concentrated ownership, a few owners, reinvestment.
And that's why you see them often in their 60s or 70s, because they've been doing it their whole life. And they started with one store and then maybe two stores and then they just slowly growing over time.
Ben Felix: The concentrated wealth thing is so interesting because we talk about this too. We talk about the benefits of diversification when you're investing, but to get to the next level of wealth, it really does often take that concentration.
Owen Zidar: And that's riskier. Don't get me wrong. That's certainly an aspect to it.
But one thing that's pretty interesting is that we not only in the series of research papers that the book is based on tracked all the wealthy people, we also tracked everyone who's starting. So say like take every single entrepreneur, there's 10 million of them who started a business since 2000 and see how well they do accounting for the fact that this is risky, including all the people who flame out and get a zero. And on average, they make a lot more money.
I think it's like 18k more. The median person also makes more money by 5k. And like often you see the people who fail, don't actually fail in a sense that they'll get a job basically doing what they were doing before, but not that big of a hit financially.
And so you get this big upside but the downside is actually not quite as bad, just from a statistical point of view. It could be quite stressful. But the risk is a lot more upside when you look at the data on all entrepreneurs in America.
Ben Felix: Kind of makes sense, I guess, because if you go and start a business and you run it for a bit, even if it's not successful, you probably gain a lot of skills. You can go work for somebody else using that expertise. So you do have that sort of downside hedge from your human capital that you build as you're trying to run your business.
Owen Zidar: Absolutely. In fact, one of my best friends, he had this great business. He raised tens of millions of dollars, had a great team, hired designers from Apple.
They were building ready-to-deploy apartment buildings. And it just turned out that the macro factors worked against him and interest rates went up and no one was building large properties. And so even though he had a great team and a pretty good idea, it just wasn't going to happen.
And it turns out he shifted. Now he's the COO of a very big private company because he learned how to run a complex organization. And it's exactly like you said.
Ben Felix: Yeah, it's a really interesting point. Who is on track to reach the 1% of the income and wealth distribution?
Owen Zidar: It depends on what trajectory you want to take. But I think one of the things that really jumped out in that entrepreneur work is that people who start out in an industry where you're likely to become an entrepreneur 10 or 15 years down the line are much better suited to make that jump into being rich in their life. You can imagine comparing two people, somebody who goes into auto repair or someone who goes into auto manufacturing.
The auto repair guy, if you look at people who work in that industry early on in their career, they're way more likely to own something by the time they're 40 versus working for Ford or GM or one of these car companies. You're not likely to be an owner, even though they seem pretty similar from the perspective of a 20-something. So if you're thinking about that as a parent, what advice to give to your kids or someone early on in their career, this early labor market domain expertise is really quite important for putting you on the track to own.
And then a second group is people mid-career who they're earning a salary. And the way you get rich is by owning, not earning, typically. So it's pretty hard to get rich getting a W-2, which is the tax form for wage payments.
So that's the more intermediate answer, depending on when you're answering the question.
Owen Zidar: It's really hard to measure consumption of the wealthy in a systematic way.
That's something that we wanted to do really well for the book and ultimately couldn't nail it systematically. There's a lot of anecdotes and there's a lot of conventional wisdom. So one view is the Millionaire Next Door book, which is this best-selling book from a few decades ago that was based on marketing data.
And it really emphasized the frugality of wealthy individuals. Like you can't tell that your neighbor is a millionaire because they're driving an ordinary car. They're kind of living within their means.
They don't have a nice watch, et cetera. There's some truth to that in the stories that we collected by talking to people. Like there are periods in a lot of these everywhere millionaires' lives where they were just hustling, not really doing much, but then later in their life, they have a superyacht.
So it depends a little bit on when you're looking. And there's certainly a lot of these folks in the private jet data and the superyacht data. And so I don't think the case is quite as clear that everyone's really frugal all the time among the rich.
I think there is a mix. Another reason why it's hard to know is that wealthy people don't answer surveys. And so it's just hard to measure this in a systematic way that we were comfortable saying, like, here's the bottom line empirically.
But that's what I can tell you from some anecdotes and relative to the conventional wisdom.
Ben Felix: Yeah, that's interesting though. What about time use? How do the wealthy spend their time?
Owen Zidar: A lot of them work and they don't like hobbies. There's several stories. One woman we talked to, she found herself and she's like, I don't want to spend the next 10 years of my life playing tennis.
I like want to do something. And she started a frozen quiche business that really grew to some serious scale. She's called the Queen of Quiche.
Other people try to have hobbies, this guy named John Osher, he sold one of his businesses and tried to retire and just couldn't do it, couldn't sit still. And then finally started another business that kind of built on what he had done before. So I think the first business was spin pops.
It's like suckers that kind of rotate so that the kid can eat it. And he had all these contacts with manufacturers in China. And then he realized that there's kind of this market by walking the halls of Walmart and figuring out there's this market for electric toothbrushes that don't cost a hundred dollars.
And he just used the same spin pop contacts in China to make a toothbrush that was affordable. He just has that itch. And so some of it, they work a lot.
And most people are not inherited owners of their family business. That's like a quarter of the people we're talking about. And so most of them kind of grew this thing.
And their stories of one of the people we talked to is like, oh, I confused Tuesdays and Saturdays because that's all kind of the same to me. Now, not everyone is like that. One guy we talked to in the book, he said, you can either have fun during the week or fun during the weekend.
He's like, I ran a paper storage business so I could have fun during the weekend. Paper storage business literally just stored important financial documents. We're going to make sure it doesn't burn. That's safe.
Ben Felix: Can you talk a little bit about the data that the book is based on? Like you mentioned some treasury data, you're talking about surveys. Can you, for the benefit of listeners, just talk a little bit about what the conclusions from the book are based on?
Owen Zidar: We have some of the coolest data that's ever been assembled on the rich in America. So in 2014, myself and Eric Zwick, who I wrote the book with, along with Danny Yagan, we were all just graduated from our PhDs. And the treasury brought us in to try to answer a narrow question, how much tax do private business owners pay?
And in exchange, we started building research projects on the full set of businesses in America. Some of the foundation is a decade of work on top incomes, top wealth, entrepreneurship, that have the full population of every single firm in America and every single person in America who files a tax return. So that's the underlying stuff.
And then there are a bunch of insights that we've put together through that. And for the book, we built on those findings to try to find individuals, because you can't do that in the tax data. It's de-identified and it's a felony to try to find individuals.
But what you can do is say, okay, I know if you cut by industry, auto dealers show up in the top group. So let's look at some auto dealers and trade publications or yacht data or data on expensive homes throughout America. There's property deed records.
There's a whole wealth of other things that we have done, including interviewing people and reading memoirs, and we've combined them to have stories and statistics in the book. And that's what all these conclusions are based on.
Owen Zidar: There are several things. One is running a private business, because that's the typical way you do it. And then there are some important macro forces that have contributed to their rise.
So one is the decline in interest rates. In the turn of the 1970s to the 1980s, Paul Volcker was really wrestling with inflation to try to get inflation down. And then we entered this period called the Great Moderation, where rates were much lower.
And that really boosted valuations, both of public equities, but also private equities. You could borrow to invest much more easily. You could sell your company for more, and the future profits of your business and your eight, nine, ten were more valuable in a discounted sense.
And so that was a huge boon to the wealthy. Second, there's been pretty substantial tax cuts for private business owners that have accumulated and kind of snowballed over recent decades. There's also deregulation.
You could sell things across state lines. There's globalization. You could talk to some of the people that we did and hiring fewer people.
And there are kind of moves that allow business owners not only to grow the pie, but also to get a bigger slice of the pie. And so all of those things have contributed to wealth accumulation.
Ben Felix: Did you find in your data any common personality traits that the wealthy show when they're children?
Owen Zidar: Yes. So one concise way to do it is they're smart and illicit, kind of street smart more so than academically smart. So one super interesting fact that we did in the entrepreneur work in the middle of the book was we linked all those 10 million entrepreneurs to their standardized test scores.
So that's the SAT and ACT. You can compare a general measure of success, like how much do you earn when you're 35 to how likely are you to start a star business, which means top 10% of revenue or employment. And if you look at the standard measure of success across SAT scores, if you have the top score, you're going to make 200k if you have a 1600.
And if you have something closer to the median, it's much lower. It's like 70 or 80k. Whereas if you look at the probability you're going to do well as an entrepreneur, it's much flatter.
Basically, there's not much of a difference between getting a median SAT score and a 1600 for the probability you start a star business. Another thing that jumped out is this illicit part. And so they're a little bit more likely to fight or get into trouble with the law, which is maybe related to kind of breaking conventions or pushing the envelope a bit.
That's a little more speculative, but that is something that shows up in the data that, you know, they have a higher probability of having had some run-ins before.
Ben Felix: Interesting. I was thinking more risk seeking when you said that.
Owen Zidar: Yeah. I mean, that also I think is related.
Cameron Passmore: Where do the wealthy go to college?
Owen Zidar: So most of these folks do go to college, but you don't have to go to an elite college to become an everywhere millionaire. There are many that didn't, that we talked to. It's kind of all over and it really depends on the person.
So I'm trying to think of some of the characters we have. So Dick Portillo, the hot dog billionaire, he didn't go to college. Karen Bentlage, the tanning bed and wax distribution leader, she didn't go to college.
Beaver Aplin went to Texas A&M. Larry Miller, the auto dealer went to BYU. There are some who go to elite colleges and then end up trying to do this thing afterwards.
So like if you go to HBS or Harvard Business School or Stanford GSB or some of these other top business schools, there is this growing popularity in search funds where they basically want to raise money and go buy an HVAC company in Mississippi. It's not obvious you needed to go to Stanford to do that. You probably benefited from the ability to raise funds and some of the skills you learned, but you could just go buy one of these companies.
There's a case for doing that as well.
Ben Felix: Yeah. The access to capital thing is probably real though.
Owen Zidar: Yeah. Although one interesting thing that when we were looking at where entrepreneurs come from is we found that early labor market experience and domain expertise was actually much more important empirically than access to capital and being wealthy right when you wanted to start the thing. And so the way we did that, so for the wealthy one, we compared early workers at IPO firms.
And so the basic thought experiment is take a guy who's like employee number four versus employee number 20. They're probably pretty similar people. Just one got there earlier and number four has way more equity.
And then after the IPO, how much more likely is employee four to go and found another company versus employee 20? He's got a lot more money. How much does money matter for future success?
And we didn't see that money in that sample mattered that much, even though there's a very sharp difference in how much money employee four, employee 20 have. So that's what that's based on. There's also some evidence based on lottery winnings.
If you go in the US and look at people who've won lotteries, the probability of starting businesses isn't that different from lottery winners of big lotteries or small lotteries or no winnings at all. I do think capital matters in many cases, but it's surprisingly less important in the context we've studied than knowing how the business works.
Ben Felix: Yeah, that's very interesting. What factors explain which places foster upward mobility?
Owen Zidar: Yeah, no, so that's I think something we'd like to research a bit more. We have established some descriptive facts. So if you go across the country, there are places like Salt Lake City, where you're three times likelier to start a business if you grew up there than in other parts of the South.
Right now, we don't have a clear answer to that other than some speculation. So one thing that people say if you go to Salt Lake City, said, well, you know, there's a substantial Mormon population in Salt Lake City. And one of the things that's often a part of people's experience when they grow up in the Mormon community is proselytizing.
And so you have to go knock on doors, learn to deal with the persistence and grit of hearing no and staying at it, and I feel like that's something that contributes to successful entrepreneurship later on. Now, I don't know if that's really the thing, but that is one possible explanation that seems somewhat plausible to me.
Owen Zidar: There's all these different hypotheses for what might matter. It could be like access to capital. It could be how rich your parents were.
It could be you have mentors. Can you learn from people on how things work? You can look at gaps across different groups.
So for example, if you think it's all about money, then one puzzling thing that emerges from the data is the gap across men and women for founding. Because if it's all about like having rich parents, men and women aren't systematically to poorer parents or richer parents, yet men are much more likely to start businesses than women in the data. It's also not about college attendance because recently women are way more likely to be college graduates than men.
I mean, often like admissions committees have to fight if they want to make it 50-50 to kind of let in some more marginal men in terms of test scores relative to women because women tend to be better students. There are some puzzles. And then a few things jump out.
One is the kids of business owners are way more likely to be business owners themselves. You could drop all the ones that have a family firm. So it's not about staying in the family firm.
And the reason why you're going to be a business owner is because you are just running what your parents gave you. It's something more about exposure to this entrepreneurial human capital that I think is an important part of what's going on. And so some of the places, I also think they have more opportunity like flatter organizations where you can really see, hey, you know, I could do this myself or this is something that I could do.
That is where we are in terms of our current understanding of what's going on to explain those gaps.
Ben Felix: It makes sense when you think about if a kid grows up in that environment and sees their parent, whatever, doing entrepreneurial stuff and taking risks that they would be more likely and willing to do that and kind of know what steps to take. What do you think entrepreneurs need to be successful?
Owen Zidar: Lots of things have to go right. So some of it is luck and some of it is some grit. It's amazing for a lot of these stories.
There are a lot of times when it wasn't going to work. The queen of quiche that I talked about, her name's Nancy Mueller. She initially made quiche for Christmas parties.
She froze them and that's what she did. And then she wanted to scale it up a little bit. And eventually it was getting to such a scale that she was using washing machines to dry spinach, which is kind of gross.
When you talk to her, her dad said something like, with each box of quiche you're sending to the store, you're like shipping dollars because she was making losses. She needed to have real scale to make enough. And there were decades when it wasn't really looking great.
And then eventually she got a big store kind of like Costco or I think it was Price Chopper was the name of it at the time or like a Walmart that put in a big order. And then she finally got enough scale to really make it. But it was a long time.
And so some of it is stick-to-itiveness and really having a vision and having to pan out and also knowing when to exit. So she was pretty nervous that if you just have this concentrated customer base, they could leave. So she sold the business too, mostly worried about losing that big contract.
Cameron Passmore: How has the share of national income accruing to labor in the U.S. changed over time?
Owen Zidar: It's a striking thing to look at the labor share. I think it's really cratered nationally. And then if you focus by several points, but if you focus on pass-through owners, so these private business owners, so I guess I'll give you some broader macro facts.
If I can remember them off the top of my head, then I'll talk about the labor share within pass-through. Between 1990 and 2020, about 60% of the growth in value added, which is profits plus wages of the business sector, so that's like traditional corporations, these private businesses, 60% of that has been in these private pass-through firms. And by pass-through, I mean firms that don't face the traditional corporate tax, but instead the profits and losses of the business flow through to the owners.
And that's what's really been booming for the stats we were talking about before in terms of the top 1% share. So if you take all business activity and how big the pie is, the growth in the pie, 60% of that has been in pass-throughs. And then there's the question, okay, how much does labor get and how much does capital get?
One way to measure the pie just as a labor productivity measure, in 2000, $34,000 per worker was typical labor productivity. And then by 2021, it went to $52,000 per worker. So that was an $18,000 per worker rise in labor productivity.
And if that were evenly split between labor and capital, that'd be $9,000 each. But what you see in the data for these top-owned firms is that 15K goes to owners and only 3K went to workers. And so there was a very material decrease in the labor share.
So I think in 2000, it was something like two-thirds went to labor. And then by 2014, it was like half and half. Part of the story of what's going on here is a material decline in the labor share.
Some of that is because owners are getting a bigger slice, but it's also the pie is growing. There is some labor productivity growth.
Ben Felix: What does that development mean for the relationship between business owners and workers?
Owen Zidar: It means that an important part of why wealthy business owners are doing well is because they've kept a larger share of the slice. Now, there are lots of things going on there. Some of this, you could say, look, these are economic forces where expertise and ownership really matter.
So one example I like to give in that is imagine someone like my former colleague, Kevin Murphy. He's an amazing economist. Somebody once joked, his first language is economics.
He could just go and think about things and give you a really cogent explanation. So he does a lot of consulting work on antitrust. And so imagine you're some big company, you want to acquire another company.
And if you get Kevin to do it, he's going to raise the probability this merger happens by 10%. This is a billion dollar deal. 10% of a billion dollar deal is really valuable.
That's increasingly valuable over time as you get bigger and bigger companies and economic growth. And so Kevin getting a growing share of what's going on is not an unreasonable proposition. He's bringing a lot to the table.
And so that's part of what's going on. Another part is, this is more nefarious and it's about like a series of regulatory restrictions or things that prevent entry and competition and essentially pull up the drawbridge from other people trying to get rich in the same way that you're getting rich and exploiting that. It's hard to say that you have to kind of go by case by case to talk about what's actually going on.
But there's definitely some of that as well. It's a nuanced picture for what's going on in the economy. And I think these things can happen at the same time and both be true.
It just depends on what industry and company you're looking at.
Owen Zidar: One striking fact about the economy is almost one in five workers have a non-compete. You can make the case for some proprietary things, but for janitors or people making sandwiches, it seems pretty tough to swallow. And what it does is it lowers wages because it makes it harder for them to move and get offers from elsewhere.
And that's one of the forces that probably contributed to the developments I was just talking about of the labor share not moving up and workers not enjoying all that productivity growth that we've seen economy-wide.
Ben Felix: Jeez. I mean, it sounds like a rough picture that you're painting for labor.
Owen Zidar: The labor share is at historic lows. There are a bunch of measurement issues related to it, one of which is the rise of pass throughs, but fundamentally, they're pretty material declines and just the share of the pie that goes to workers.
Ben Felix: How do you think that resolves over time, or does it?
Owen Zidar: I think that's one of the main questions that we face as a society is can you continue to operate just without paying attention to it? And obviously, you've had very tumultuous political environments and elections and people being very upset with the state of things, not just in the US, but just everywhere in the world. And some of that could be a response to globalization and some of these forces where the share going to labor is not looking high.
If you look at AI and some predictions people have, there's plausible scenarios where that's only going to accelerate. I'm not a political scientist, but it doesn't strike me as implausible that this will continue to be a very volatile situation. And it's important to think about reasonable interventions that are good for economic growth and good for prosperity and capitalism that can make sure we don't sacrifice the ability to have a healthy economy and also make sure people get paid.
Ben Felix: This is a tough question. I'm asking you to solve the world's problems quite literally, but what are some examples like what could solve that?
Owen Zidar: You know, one thing that's a little off topic, but it's fine is the healthcare in the US, we're really unlike many other countries in terms of how we do it. They're just absolutely crushing healthcare costs for small businesses. It's very bad for business and it's very bad for their workers.
So I'm on the board of a daycare. And this year we were quoted a health insurance cost increase of 50%. Literally next year, whatever you're paying for health insurance for your employees goes up by 50%.
You're saying, okay, I'm going to tell some set of workers who are devoting their life to helping kids who are basically making the minimum wage. I'm going to take your $30,000 and then $7,000 of that is no longer going to go to you. It's going to go to health insurance company.
That seems pretty crushing. We have to figure out a way to do something about this. And in a separate work, we studied what is the effect of rising employer sponsored health insurance costs on the labor market.
And one thing that it does is it makes the US a lot less competitive. It's hard to say, I'm going to go build a plant in Ohio. If I have to pay $27,000 on top of whatever I pay that person in wages to pay for a family plan, it's not going to be something that is going to be reasonable relative to other production opportunities.
So I think the fact that healthcare is so expensive in the US and growing so rapidly makes it tough to compete and makes it tough for somebody making low income to survive. And so I think that this just has to change. So some economists who I really respect, Amy Finkelstein and Liran Einav, they have this book, trying to remember what it's called, something like We've Got You Covered.
But the basic idea is if you have an old house, there are a couple of different strategies and the old house is the healthcare system. You can like try to rebuild things and tinker around. And then their basic point is like, this is not a situation where you can just tinker with it.
We need a tear down. And you should just completely overhaul the thing. And what should you have?
Something that's simple, basic, and free. Simple meaning you don't have all these crazy institutions. Basic meaning it's kind of like the back of an airplane.
You're going to pay to get from point A to point B, but it might not be the most comfortable thing in the world. If you want a more comfortable version, you have to pay more. And free meaning you don't have all these deductibles and things because that empirically doesn't work as well as people might think.
That's one example of a place to do it. And for small business owners, if you're running a business and your costs go up by 50% on wages, it's really hard to deal with that. You can pass some of that on, but if you're small, you can't compete with a big firm that can self-insure and navigate some of this more effectively.
So I think it's also important for dynamism in the United States.
Ben Felix: Super interesting. You said that was a bit off topic, but I thought it was great. Really interesting stuff. How do inheritances shape the path to wealth?
Owen Zidar: Inheritance is a super interesting thing. So my coauthor, Eric, he's funnier than I am. He likes to joke.
He's like, that's the recommended path to getting rich. It's just, if you can inherit it, that's where you start. But it's very complicated.
In the book, we tell a couple of different stories. Basically the story of it going well and the story of it going very poorly. The one where it goes well, they were very coordinated.
The dad basically brought the son up, put him in hard jobs at the company. He was really learning the ropes. He was very smart about the transition.
During COVID, when the value of the business cratered, that's when they handed it over because for tax purposes, it was no longer eligible. It was below the exemption levels. That ended up working great.
On the other hand, we told the story of a street sweeper repair business that had a couple of brothers, one of whom was somewhat responsible and put a lot of his money in, and the other one treated it like a bank account. It was very contentious. The one brother was really at financial risk of the whole thing going under because the other one was taking it down and basically tore this family apart.
So you see a big range of paths. Other businesses employ dozens of people. So there's one family in St. Louis and I asked them at a family gathering, I was like, okay, who's the richest kid in your high school?
To one of my nephews. And they're like, oh, it's the Tracy family. I was like, okay, what does the Tracy family do?
They're a food redistributor. And the Tracy family, I think the business is called Dot Foods and they employ something like 57 Tracy family members in the thing. And so there's some cases where it seems to be a bit more harmonious, at least from the outside.
There's a range, but one other person we talked to, I think it was interesting. Her name's Annette Lareau and she is a sociologist at Penn. And she interviewed about a hundred really wealthy families who have all inherited businesses.
And her conclusion, she told me for herself, she said, if I could give my daughter $40 million or zero, I would give her zero because of all the craziness she saw. I think that's kind of my take on inherited family firms.
Ben Felix: Those are super interesting stories. Is there like a image in the data of how inheritances affect wealth?
Owen Zidar: There are several things. One fact is that it's less prevalent in the U.S. than in some other countries. Some people speculate that's one of the reasons why the U.S. economy grows faster. Warren Buffett had this joke. He was like, if you're going to select the Olympic team, would you restrict yourself to the sons and daughters of former Olympians or would you go for everybody? Some of it is about making sure more people have a shot.
You want the best people to rise up into leadership roles and you get more productivity when you have the right people running things.
Owen Zidar: There's a lot of people who are interested in buying successful businesses now. Some of it is putting yourself in the market for a lot of these hungry business school grads or people who are mid-career who want to switch and just let it be known that, hey, I have a cash-flowing business that's a good business.
If you really want to make it work, you can do seller financing so that these people can buy the business in part by using the proceeds of future profits to pay off a loan to you. To me, I find that very attractive as a potential buyer because then that signals, hey, this person really believes in their business. If they're going to basically take the promise of future profits from it, that means they believe it's going to generate future profits.
It's not some lemon. That's one key way that I would encourage business owners to think about doing it. Often, you can get better terms because it's a valuable thing.
It's not like it's a free lunch.
Ben Felix: Can you talk about the benefits and maybe also some of the problems that private equity poses to business owners?
Owen Zidar: Yes. Some of the benefits. For example, we talked to this doctor.
If you think about it from their perspective of a doctor who's had their practice bought by private equity, they can do some stuff at scale. If you're running a small practice, there's a bunch of stuff that might not be top of mind. It gets lost in the shuffle like really being on top of billing and getting paid right away by everybody efficiently.
If you have a private equity firm that has a portfolio of these businesses, they might have some larger scale where they could say, look, this is what's working for our four or five other practices. We're going to put you on this billing provider, and then you can get efficiencies that way. That's the type of thing that I think works pretty well.
You can also benefit from knowledge of their other portfolio companies. Say you're navigating some issue with financing or some other strategic issue, there's probably somebody else who's dealt with this, or maybe you want some more customers. They can put you in touch with customers.
There are a lot of things that they can help with, but there might also be a lot more pressure or there are material pay differences. This doctor, I remember he complained he was getting $500,000 less in annual income, which also goes to show you how much doctors make, that you could have a Delta 500k and still be making doctor salary because he became an owner rather than getting the salary. So there's some in terms of what the pay looks like as well.
So you need to be prepared for that. You might also lose some culture. You might have to make harder decisions about losing employees.
Maybe you lose control. Maybe the business is going to go in a direction that you didn't want to take it and that's too bad. You've lost the ability to have that autonomy.
Owen Zidar: I think one great use as an exit option to avoid some of those family dynamics that I was talking about before, often they're very hungry for these types of businesses. My first job, I worked at Bain Capital, which was pretty early at this. I think one of the first, if not the first investments of Bain Capital was Staples.
This is basically an everywhere millionaire business when it was smaller. It's like they sold office equipment, office supplies. Mitt Romney really helped grow that business well.
And so I think some of the strategic support, some of the financing partnerships, bringing customers to people, I think those are all pretty real.
Ben Felix: Can you talk about the effect of stealth consolidation?
Owen Zidar: Yes. There's a former colleague of mine, Thomas Wollman, who has some great work on stealth consolidation. The basic idea is that the benchmark for what flags a review from the FTC is kind of a nominal threshold. So below that threshold, there's a lot of roll-ups and mergers that happen without review.
And his basic point is, if you look kind of below the threshold, there's been a ton of consolidation in industries and that's driven up prices and not always been to the benefit of customers. And so if you think about some of the objectives of the Federal Trade Commission, should really look below that threshold and maybe consider lowering it because there's been a lot of stealth consolidation. Things like dialysis.
He has a bunch of examples that I'm not remembering off the top of my head, but that's the basic idea.
Ben Felix: So is that like private equity roll-ups? They're just buying small private businesses and rolling them up into under one entity.
Owen Zidar: Yes. So sometimes, or it's just not necessarily private equity, just a series of veterinarians. They're going to buy up a bunch of things.
And then all of a sudden, they're like, look, we control the local market for vet services. We're going to raise prices by 20%. That doesn't have to have anything to do with private equity, just local consolidation.
Ben Felix: Interesting. Do you think that affects labor markets too?
Owen Zidar: Yes. So there's some suggestive evidence that when firms have product market power, they can also have some labor market power. That's part of the story for the decline of the labor share.
How big it is, it's hard to quantify all these things on an equal footing, but I think that's part of what's going on. But again, that's very different than the, oh, we need to focus on big tech and the five largest firms that are driving the stock market for breaking them up. This is way more of a local on the ground regional story.
Ben Felix: It happens like everywhere where we live. In Canada, you see it with dental clinics, dermatology clinics, a lot of medical stuff, veterinarians, like you said, it's happening a lot. Just so you can see it.
Owen Zidar: I mean, some of these markets are huge. And so dentists, for example, one of my favorite facts about dentists, if you add up all the revenues of dentists in the United States, it's much larger than the total revenue of the NBA, the NHL, the NFL, MLB, all pro sports teams combined, just dentists make a ton of money. It's just not something you think about.
But then when you kind of take a step back, you're like, all right, everybody has teeth. It does make sense. And if you see this product market power emerging at the local level, can raise prices.
They're also pretty effective at fighting political forces to hold prices down. So there's some move in the US to include dental services in Medicare, but dentists fought it because they didn't want the price pressure of the US government being able to say, all right, no, no, no, we're not going to pay that much year after year. And so that's one example of their political clout.
Cameron Passmore: You mentioned the Great Gatsby earlier. Is the US in a new Gilded Age?
Owen Zidar: That's a great question. So there's certainly some things that would make you think that, and many people like Paul Krugman and others have emphasized that we're in a new Gilded Age. So for example, if you look at top income shares, they look just like they did when we first started recording them.
The US modern tax started in 1913. And so it's a little bit after the Gilded Age, but we're back even a little above the levels of concentration for the top 0.1% and top 1% that we had at the beginning of the 20th century. And there's this perception that there's just a small number of Rockefellers and Carnegie types that are dominating the news.
But we're quite different in many ways. Many of these everywhere millionaires are not doing transformational innovation. They're making hot dogs or garage doors or cleaning teeth.
So that's pretty different than like building transcontinental railroads or the first type of kind of grand, very capital intensive investments. We're in a service economy that's quite different than the economy of the Gilded Age. And so we like to emphasize that we're kind of in this new age of millionaires where there's just an abundance of wealth and prosperity across America.
And we're often obsessed with a few billionaires who have been monopolizing attention, but they really do not monopolize wealth in America.
Owen Zidar: Yes. So there are a couple of reasons why we call them everywhere millionaires. So you find them in any town in America.
In terms of political power, there's also an everywhere millionaire in basically every congressional district. And so when you think about who is the senator or who is the member of Congress or who plays golf with the member of Congress, who employs a lot of people in the district? Think about all the sales tax revenue.
So auto dealers, for example, employ something like 10% of retail employment. They bring in something like 20% of state sales taxes. These are pretty important people from the perspective of the governor, the congressperson, or the mayor.
It's a lot of jobs, it's a lot of money, and they have a lot of influence as a result of that. That's pretty different than Elon Musk, who donated a ton of money in elections and got a DOGE. But when you look at what actually happened in terms of concrete policy, so take the One Big Beautiful Bill Act, Elon Musk was a loser in that he lost a lot of clean energy credits, the EV incentives were cut, and then the kind of everywhere millionaire auto dealer got 7% deduction on their taxes, so from 37 to 30 preserved.
They got a workaround from some caps on state taxes. They got a special new deduction where if you buy a new car, you can deduct from your taxes the loan you took out to buy it. I think when you actually look at the details of what happens, you should be focusing much more on this group of people because their influence rivals that of the much more in the news billionaires that some people are very worried about.
Ben Felix: So I just didn't think about why this is an interesting topic for a book. You don't hear about those people or people don't worry about them. People worry about, like you said, Elon Musk.
Owen Zidar: For a good reason, but at the same time, once you see it, you kind of see it everywhere. So one of our hopes in writing the book is that one is to inspire people because there are some really inspirational stories about business owners who rise from the bottom to the top and bring a lot of good people with them. And I think we should have more millionaires in America.
We should have more people who have a shot at becoming millionaires. But also, we should be quite aware of how powerful this group can also be. Very careful about things that are kind of, we need to make sure small business or the little guy is okay because that's been the Trojan horse that's led to a lot of problems.
Once you kind of recognize this, you see it everywhere in political debates if you kind of follow the details of how some things shake out.
Cameron Passmore: How important are interest rates in driving increases in wealth?
Owen Zidar: They're central. They're one of the most important macro factors. When rates came down with the Great Moderation after Paul Volcker, that was the first order cause of a lot of the boom in the stock market and in private business valuations.
Ben Felix: Are there implications of that?
Owen Zidar: One thing is when you think about what's really going on with top wealth, you need to make a distinction of flows versus stocks. And the flows might not have changed that much, but the stocks change a lot if you're changing the discount rate for future cash flows. So when you see that, oh, wealth doubled, that doesn't necessarily mean that the annual profits doubled.
From the perspective of business owners, they may be like, look, my flows are the same. I don't feel as rich as you say I am on paper. So that's one thing that you might get as an upshot of interest rate movements causing a lot of the rise and wealth accumulation.
Ben Felix: How can more people be helped to climb the ladder of financial success?
Owen Zidar: Yeah. So I think some is really getting a lot of people early labor market experience that puts them on a path to be at these more entrepreneurial sectors. That is one quite important thing that we should consider how to do that better because it does seem like exposure.
If you're, as we were talking about before, if your parents are business owners, you're much more likely to become a business owner yourself. So exposure to this type of experience, I think is quite key. So more apprenticeship type opportunities and a more thoughtful cultivation of upward paths and careers that aren't necessarily in the conventional, study hard, go to a good college, go to a name brand firm and earn a salary.
Thinking about these alternative paths, I think is a way to do that.
Owen Zidar: There is this pretty interesting study out of Harvard Business School. The way Harvard Business School is set up, and my coauthor, Eric Zwick went there so I can learn some of these fun stories from him. It's set up in sections.
And so you kind of have this small group of people that you kind of take everything with. They looked at entrepreneurs who were placed in sections, which, the allocations are random. Some of them were in sections where someone else had entrepreneurial experience.
And some were in groups that didn't have any people with former experience. And what you found is that people who are in sections with somebody with experience, they're much less likely to start something. But conditional on starting it, they're much more likely to succeed.
And so it seemed like talking to people who've done this type of thing before and really vetting ideas is an important way to achieve what you asked of having entrepreneurs have less risk and more success. So it's basically getting exposure to people who have done this before is one thing that seems to work.
Ben Felix: What do you think are some of the practical steps that could be taken in the US to reduce inequality, but preserve the ability of business owners to hire and fire workers?
Owen Zidar: So first, this book is not a policy book. We very actively tried not to do that. I think about these things a lot, but I'll just rattle off a few.
So one, we talked about health insurance and healthcare reform. Another is just basically resetting the tax code back to what it was in 1997. We jokingly call it, "party like it's 1997."
Growth was very high then we had surpluses, not deficits, and we'd raised trillions of dollars to go back to that era. Some of the cuts that we've had just have not been that effective at generating new employment and investment. And so we think some reset is appropriate, mostly on the individual side.
Another is that we haven't raised the minimum wage in decades. It doesn't have to be astronomically high, but if just set what it was with inflation is a reasonable benchmark, and there's some pretty good empirical work looking at the effects on businesses and what actually happens, a lot of it gets passed through to consumers or the owners eat it. So if you're thinking about that question about the labor share and some of the dynamics, I think that would do some work to offset those dynamics a little bit without having a major drag on productivity and employment and investment.
Because I do think when people talk about policy solutions, they really should be quite cautious about shrinking the pie. And that's something I care quite a bit about. So we have some work, for example, showing parts of the 2017 tax reform really stimulated a lot of investment.
I do think we need to think about outcomes when we're talking about policy. And so there's some things that work quite well, and we need to focus our resources on that. And then the stuff that doesn't work, we really need to question it.
So the stuff that doesn't work as well, or this 7% deduction for business owners that cost a trillion dollars that was preserved in the 2025 bill, that's the type of thing we can't afford right now. But some of the investment incentives did seem to be more effective, and so I would keep those.
Cameron Passmore: Really interesting. Final question for you, Owen. How do you define success in your life?
Owen Zidar: There's a couple different dimensions. One is having a happy and healthy family. I'm blessed with three young kids and a wife.
We have three, they're all under five, and so it's pretty chaotic at the moment. So sleep, I basically have, my answers have just been hours of sleep is my current measure of happiness. No, but working in a profession where I can try to work on things that I'm interested in and let more people know about ways that we can make the economy work better and have policy work better and give people a shot.
Because I do think learning about some of these stories is pretty inspiring. And so I'd like more people to be able to prosper in their lives. And so having healthy family, healthy and exciting job where you can help other people, I think are two measures of success that I think about.
Cameron Passmore: Love it. This was a great conversation. Congratulations on your book and this research. It's fascinating.
Owen Zidar: Thank you so much.
Ben Felix: You'll sleep eventually, don't worry.
Cameron Passmore: Yeah.
Ben Felix: I've got four kids under 11 now.
Owen Zidar: Oh, wow.
Ben Felix: At one point I did have three kids under five. I didn't sleep either, but you'll sleep one day.
Owen Zidar: I can look forward to that. Awesome. Well, thank you all so much for having me.
It's been a real pleasure talking to you.
Cameron Passmore: Love it. Take care.
Ben Felix: Thanks, Owen.
Cameron Passmore: You know, Ben, it's got to be 30 plus years ago where we were presented in our office, this is way back in the old mutual fund days, the book called The Millionaire Next Door. And that was my first introduction to the thinking around like, who is the average millionaire out there and what do they do and where did the wealth come from and what are their habits and where do they drive and where do they eat and how do they spend? And I remember finding that book so fascinating.
Of course, it was presented to us as a way to help us connect and find our potential future clients, but I can remember that day like yesterday being presented with that book by Dr. Tom Stanley was either the author or co-author of that book. And then to have this conversation today with Owen, it's like, wow, just being right back in time, but with this unbelievably modern set of data.
Ben Felix: He took the premise of that book and gave it an economist's treatment. And as he talks about, they got their hands on data that just nobody else has had before. And so they were able to build that incredible profile of what typical millionaire looks like.
And then I love the combining the data work they did, the empirical work they did with conversations, with the everyday millionaires that they identified to understand all that stuff, like about how they spend their money and how they spend their time, who they are. I love the hustle part. Maybe that's because I like to work a lot too, but just the idea that they're just regular people that work really hard, work a lot, don't like to stop working, don't necessarily spend lavishly, but as he talked about, some do.
Cameron Passmore: Some do. And some have very conservative lifestyles through most of their working lives. And at the end, they really go and live it up.
It's interesting, like in our roles, we get front row seat to seeing how people with some pretty good savings, how they do spend their money. But what I think we find more interesting is how they earned their money. And we have so many examples of businesses where you just go, huh, I never even knew that thing, that need, existed.
They build these unbelievable enterprises completely under the radar. And we have many of those cases. Yeah, we've got some technology people that have hit it there, but to see these businesses that you had no idea existed at all.
Ben Felix: Some of it's professionals that he talked about, dentists, doctors, lawyers, professionals. To your point, Cameron, we have so many interesting cases where the client has a business that, like you said, you didn't even know that was a thing that existed, but of course it does. Someone's got to do that super niche or not fun to do thing.
As Owen talked about, people that do those things can make a whole whack of money doing it. A little bit more on Owen, we gave him a very brief introduction, but he is a Professor of Economics and Public Affairs at Princeton, jointly appointed in the Economics Department in the School of Public and International Affairs. Prior to Princeton, he was an assistant professor at Chicago Booth, where we've had many guests from.
He's also a staff economist at the Council of Economic Advisors and an analyst at Bain Capital, which he did mention. He got his PhD from UC Berkeley. Super interesting conversation.
He's got a book, which of course we were talking about. We get a lot of folks reaching out wanting to talk about their books and we don't usually have them on because they're not usually economists with really data-driven things to talk about. When I saw this one come in, I took a quick flip through it and it was pretty obvious it would be an interesting conversation, which I think it was.
Cameron Passmore: I agree. Anything else, Ben, you want to add?
Ben Felix: I'm curious on your thoughts, Cameron, on just the value of entrepreneurship. You've lived that life. You're still living it on a different side of it now.
Cameron Passmore: He talked about the decades of grinding. This is something Seinfeld talks about a lot. It's like to find something that most people would find drudgery, that you just love doing, you keep working at that craft for years and years.
As I found myself thinking, look back on 35 years of doing this, it's just unbelievable to me that, hey, I did it 30 years in PWL alone and to have loved all of it. It's just that continual grind through years. You combine with that some of the habits that David Booth talked about when he joined us, just the compounding effect of working at a craft and then trying to squirrel some money away as you go along.
It's just a lifelong pursuit. Is it entrepreneurship? I guess so, but it's like to find something you love doing that others might not want to do.
It's just pretty cool to be lucky enough to have found this career.
Ben Felix: I think in your case, it's definitely been entrepreneurship. Even when we met 13 or so years ago, you were not in the same position that you're in. You were still grinding.
You were still in the middle of the grind. It's so interesting to think about the compounding effects that you don't see. When we met, it was not obvious that you were building the business that we ended up building.
You had your head down, you were grinding, you kept grinding. Then it almost seems like, and it's not like that, but it almost seems like all of a sudden, it was this incredible business. That's just the long-term effect of compounding and grinding and keeping your head down and working your butt off and some luck in making good decisions.
Cameron Passmore: It's interesting because we talked about this last week. We had our annual summit that were 150 plus or minus of us were in one place. It was one thing to look back 13 years when it was a handful of us and it was all our individual hustle.
It's almost like entrepreneurship is the ability to keep up that vision as you keep growing and empower a team to keep up. I'm talking about the flywheels to keep up what was started 30 plus years ago, but to go from a handful of people to like a ballroom full of people, it's a whole different game. What we're doing is incredible and desperately needed by so many people.
What we represent, the simple concept of markets work and planning really matters. It's so desperately needed. The mission is clear, but it's to take that and to empower and energize and give the vision to 150 people to hopefully 300 people in the near future.
I had no idea this was at all possible when you and I first met. You think back, I mean, and we're kind of riffing on different stuff here, but back in the day before you even joined, we used to have an annual client seminar. We get 80 people out, a hundred people out, and it was expensive and it was a lot of hustle.
We thought that was pretty good. Now, how many people a month are listening to this and to your YouTube channel? It's in the hundreds of thousands, if not in the millions.
It's just a whole different scale. Same basic belief system. It's just the scale of what you can create by keeping your head down, that compounding effect for years and decades.
It's incredible.
Ben Felix: Keeping your head down, trying stuff, some luck for sure, but it's a silent compounding. You're grinding, you're doing stuff, and then all of a sudden you have a valuable, successful business.
Cameron Passmore: And you keep grinding and compounding, but it's really, as I always say, it's the unintended outcomes, the unintended consequences, the stuff that happens, the accidental meeting, the accidental whatever that might happen that you say, wow, you couldn't have planned for that. But if you weren't grinding and had your head down and open up these opportunities, it never would have happened. But as we said last week, 30 years and we're just getting started.
Ben Felix: So interesting to think about. We talked a little about the consolidation that Owen talked about, super interesting, but also just people know I've done a bunch of house renovation type stuff. And you look at the people in trades who are scaling businesses.
There are individual trades people that make a good living, whatever. But then there are others who are scaling their business, taking on lots of clients, hiring the right people to help them build a business. And they can turn into really, really successful businesses really quickly, but they're not the kind of thing that people think about when they think about how do you get wealthy.
Cameron Passmore: I agree.
Ben Felix: Great message from Owen. As we said already, his data, his ability to take data to that great message is something that I don't think has been done before as he talked about.
So hopefully listeners enjoyed it.
Cameron Passmore: Love it. And as always, thanks for listening.
Disclaimer:
Portfolio management and brokerage services in Canada are offered exclusively by PWL Capital, Inc. (“PWL Capital”) which is regulated by the Canadian Investment Regulatory Organization (CIRO) and is a member of the Canadian Investor Protection Fund (CIPF). Investment advisory services in the United States of America are offered exclusively by OneDigital Investment Advisors LLC (“OneDigital”). OneDigital and PWL Capital are affiliated entities, and they mostly get on really well with each other. However, each company has financial responsibility for only its own products and services.
Nothing herein constitutes an offer or solicitation to buy or sell any security. Occasionally we tell you not to buy crappy investments in the first place, but that’s not the same thing as telling you to sell them.
This communication is distributed for informational purposes only; the information contained herein has been derived from sources believed to be “truthy,” but not necessarily accurate. We really do try, but we can’t make any guarantees. Even if nothing we say is fundamentally wrong, it might not be the whole story.
Furthermore, nothing herein should be construed as investment, tax or legal advice. Even though we call the podcast “your weekly reality check on sensible investing and financial decision making,” you should not rely on us when making actual decisions, only hypothetical ones.
Different types of investments and investment strategies have varying degrees of risk and are not suitable for all investors. You should consult with a professional adviser to see how the information contained herein may apply to your individual circumstances. It might not apply at all. Honestly, you can probably ignore most of it.
All market indices discussed are unmanaged, do not incur management fees, and cannot be invested in directly. Which is a shame, because it would be awesome if you could.
All investing involves risk of loss: including loss of money, loss of sleep, loss of hair, and loss of reputation. Nothing herein should be construed as a guarantee of any specific outcome or profit.
Past performance is not indicative of or a guarantee of future results. If it were, it would be much easier to be a Leafs fan.
All statements and opinions presented herein are those of the individual hosts and/or guests, are current only as of this communication’s original publication date. No one should be surprised if they have all since recanted. Neither OneDigital nor PWL Capital has any obligation to provide revised statements and/or opinions in the event of changed circumstances.
Is there an error in the transcript? Let us know! Email us at info@rationalreminder.ca.
Be sure to add the episode number for reference.
Participate in our Community Discussion about this Episode:
Sources From Today’s Episode:
https://zbib.org/75a6ae2e79a34ba8b5fb632f54816447
Books From Today’s Episode:
The Everywhere Millionaire: Who Is Really Rich in America and How They Got There by Owen Zidar — https://www.amazon.com/dp/1250378508?lv=shuf&channelId=500&plpRedirect=mhFallback
Links From Today’s Episode:
Stay Safe From Scams — https://pwlcapital.com/stay-safe-online/
Rational Reminder on Apple Podcasts — https://itunes.apple.com/ca/podcast/the-rational-reminder-podcast/id1426530582.
Rational Reminder on Spotify —https://open.spotify.com/show/6RHWTH9iW7hdnA7eAg7ukO?si=fe7f60349b584026
Rational Reminder on Instagram — https://www.instagram.com/rationalreminder/
Rational Reminder on YouTube — https://www.youtube.com/channel/
Benjamin Felix — https://pwlcapital.com/our-team/
Benjamin on X — https://x.com/benjaminfelix
Benjamin on LinkedIn — https://www.linkedin.com/in/benjaminwfelix/
Owen's website — https://www.everywheremillionaire.com/
Owen on LinkedIn — https://www.linkedin.com/in/owenzidar/