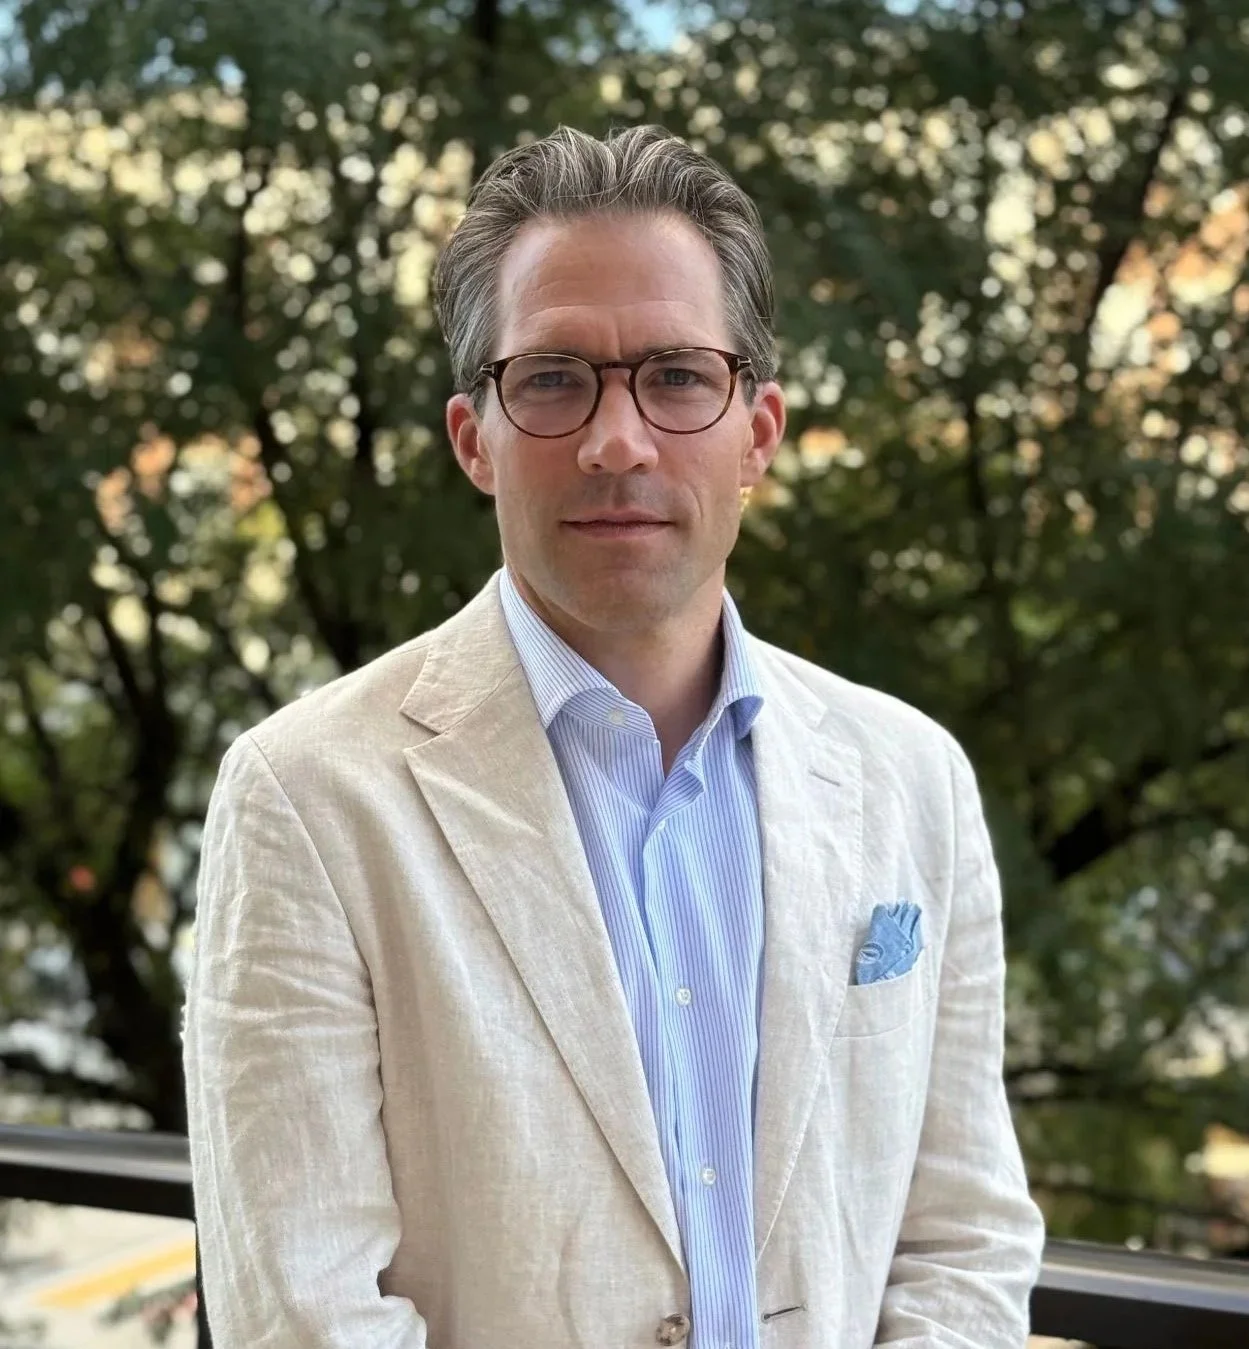
Martin is Professor of Finance, Economics, and Real Estate at the University of Oxford's Saïd Business School, former head of the school's Finance, Accounting, Management Science, and Economics area, and former Chief Economist of the Public Company Accounting Oversight Board -- the audit regulator in Washington, D.C., protecting over $70 trillion of investor capital. Martin also serves as Chairman of a large family office. An engineer by training, he holds a PhD in Economics from Princeton University.
His research portfolio is unusually broad; it includes theory and empirics and ranges from behavioral finance (theories of overconfidence and time-inconsistent investor behavior) to corporate finance and asset pricing. Most of it features strategic interactions between various players of the corporate ecosystem. He is best known for his work "common ownership" of competitors which brings the analysis of strategic interactions to the finance literature, and for researching possible social costs of investor diversification. This strand of research has affected policy making and antitrust enforcement worldwide.
In this episode, we’re joined by Martin Schmalz, Professor of Finance, Economics, and Real Estate at the University of Oxford’s Saïd Business School, for a wide-ranging conversation about index funds, common ownership, investor behavior, and wealth management. Martin’s research challenges us to look beyond the benefits of indexing for individual investors and consider what happens when everyone makes the same rational choice. Could the growth of index funds affect asset prices, expected returns, and competition between companies?
We explore the equilibrium effects of indexing, how common ownership might influence competition and consumer prices, and what existing antitrust laws could mean for large institutional shareholders. Martin also explains why wealth creation and wealth preservation require different mindsets, why wealthy investors can struggle to embrace passive investing, and how delegated investment management can help people stick with an investment plan when markets become uncomfortable. We finish with a discussion of family offices, the compounding impact of costs, and Martin’s thoughts on why thinking like an economist might not always make us happier.
Key Points From This Episode:
(0:01:13) Why indexing has been such a valuable innovation for investors, and the central question of whether its widespread adoption creates unintended market-wide consequences.
(0:03:24) Why the equilibrium effects of indexing matter more than simply comparing index funds with individual stock picking.
(0:05:55) How lower-cost indexing changes investor behavior, asset demand, stock prices, and expected returns.
(0:08:35) The possibility that greater demand for diversified equities raises prices and lowers future expected returns.
(0:12:03) Why the impact of indexing differs across investors depending on wealth, risk aversion, and asset holdings.
(0:13:35) Indexing as a potential tragedy of the commons, where individually rational decisions may have collective effects.
(0:15:15) The theory of common ownership and concerns about competition when the same investors own competing firms.
(0:19:05) Why common ownership is not solely an index-fund phenomenon, with active investors, family offices, and other large owners also playing a major role.
(0:23:11) What airline-industry research suggests about the relationship between common ownership and consumer prices.
(0:28:00) Competing explanations for the evidence on common ownership, including weaker monitoring and reduced incentives to compete aggressively.
(0:31:31) Why theoretical models should not be treated as proof of real-world outcomes.
(0:35:14) How existing antitrust laws, including the Hart-Scott-Rodino Act, Sherman Act, and Clayton Act, relate to common ownership.
(0:38:00) Potential policy responses, including ownership restrictions and limits on voting rights.
(0:41:32) Why many wealthy investors fail to index, and how the skills that create wealth often differ from those required to preserve it.
(0:46:00) The costs of poor diversification, excessive trading, market-timing mistakes, and inadequate due diligence.
(0:49:59) Horizon-dependent risk aversion: why people become more risk-averse when potential losses feel immediate.
(0:55:46) Why delegated investment management can act as a commitment device that helps investors avoid costly behavioral mistakes.
(0:58:39) How wealthy investors and family offices can still fall victim to expensive products, complexity, and poor decision-making.
(1:02:00) The compounding cost of fees and complexity, and why simple, diversified portfolios may outperform many private-market approaches.
(1:08:35) Why economic thinking is powerful for markets but may be less useful for personal happiness, leading to a broader discussion of success, well-being, and creating value for future generations.
Read The Transcript:
Ben Felix: Welcome to episode 435 of the Rational Reminder podcast. I'm Ben Felix, Chief Investment Officer at PWL Capital.
Cameron Passmore: And I'm Cameron Passmore, Chief Executive Officer at PWL Capital. And today we are joined by Martin Schmalz.
Ben Felix: Martin is a German economist and professor of finance, economics and real estate at the University of Oxford's Saïd Business School. His research spans asset management, asset pricing and investor behavior. He is best known for his work on common ownership, which is when one set of shareholders owns competing companies as index fund investors do.
Cameron Passmore: We talk about whether index funds for all their benefits carry hidden costs for investors and the broader economy. From there, we turn to investor behavior and why wealthy investors often avoid the cheap diversified portfolios that research supports. We finish on a personal note with why thinking like an economist can make you unhappy.
Ben Felix: Well, we'll share our thoughts at the end of the episode, but for now, let's go to our conversation with Martin. Martin Schmalz, welcome to the Rational Reminder Podcast.
Martin Schmalz: Thanks very much for having me.
Ben Felix: We're very excited to be talking to you. Martin, why has index investing grown to its current scale?
Martin Schmalz: Mostly because it's an incredibly valuable product offered at a very low price. Economists have these theories of how when things are cheap people buy a lot of it. So I think that must be the main reason.
So thanks to Jack Bogle, I think the genius of it was not just the product itself, but also how you set up the firm, basically making it a cooperative, a customer owned corporation, which I just conjecture without evidence might be behind them offering the product at cost, as opposed to trying to extract the highest margin out of the value they create. I think we all have to thank him for that.
Cameron Passmore: How do you think about how good a deal indexing really is for the individual investor?
Martin Schmalz: I think your audience is used to that statement, but it's hundreds of billions of dollars of fees saved. And not just that, it also just pulled in people into the stock market that otherwise wouldn't have any exposure. If we know anything about the drivers of wealth inequality on Earth these days, a lot of it is driven by stock market participation. One would think that it's been an unbelievably good deal for the average individual investor.
Ben Felix: We're asking about a paper that you have that asks an interesting question about index funds. If index funds are good for each individual investor, why is it worth asking whether they're good overall?
Martin Schmalz: That's where the heresy starts. Yeah. So you're referring to a paper, it started with Bill Zame at UCLA, and it's titled something like Do Index Funds Benefit Investors.
And that's a strange question to ask given what I just said about how wonderful it is. But the question is whether it's good in equilibrium. So it might be good for every individual, but it might have equilibrium effects that are not actually good for each individual investor.
We might all be better off without them. That's a theoretical possibility we lay out here. Let me be clear about this.
But of course, we could also ask about externalities that indexing could have on other stakeholders, so non-investors, such as consumers. That raises a whole host of issues that traditional finance has just ignored for the last 100 years.
Cameron Passmore: How does indexing affect asset prices?
Martin Schmalz: So I think there's quite a bit of evidence and simple theory as well that indexing increases asset prices.
The simple model goes, you have a certain amount of supply of equities out there. So a number of companies with a certain number of outstanding stock. And if you make holding that stock more attractive, for example, by making it cheaper to hold the diversified portfolio, that's a whole point of indexing.
So you hold supply constant, you increase demand, what happens to price? That's just Econ 101 that the price will go up in financial economics terms, just the risk premium in the market will just go down when you make it cheaper to diversify, because the individual investors hold less risk. So it stands to reason, and there's a whole bunch of evidence from indexing collusion effects and so forth that companies that are captured by the index have lower costs of capital.
That's a good side from the corporate finance side. But of course, it means for the investor it has lower expected returns as well. The fun intellectual question that arises is this.
So through indexing, you have less risk than if you held individual stocks and were exposed to idiosyncratic risk. That's a good thing for investor welfare, of course. But you also have lower expected returns, which is kind of like a bad thing for investors.
And the question is which of these effects dominates in equilibrium. And this is where at least my intuition runs out. And that's why one needs a model to figure out the answer to that. That's what I've been trying to do with Bill Zame.
Ben Felix: I do want to ask about the model. You mentioned this being heretical. What kind of feedback have you gotten from people when they see this paper?
Martin Schmalz: They are honestly upset at the question one asks about whether indexing is good for investors. Again, because I mean, look, we've trained ourselves for a few decades now into believing and for good reason that indexing is good for individuals. I'm also not challenging that notion.
Everybody who listens and everybody you talk to, nothing is changed about the fact that if you run across someone who holds a lot of individual stocks, not knowing about index funds, and it's a good thing for that person to instead hold an index fund and get cheaper diversification. Just nobody has asked the question what the equilibrium effects of that might be and what the welfare effects are. So I think lots of it is really just misunderstanding the question we ask and that there's actually a bit more thought and not really anything that overturns conventional wisdom, but really just expands on it.
Ben Felix: Tell us how the model is set up.
Martin Schmalz: So there's a few models because we were trying to understand how robust the results are, In the simplest version of it you just think that you have a fixed number of firms that have a fixed number of stock outstanding.
They have a fixed profit-generating process, or pay dividends, whatever it might be. All of that is held fixed. So that's the supply of stocks part.
And then there is a continuum of investors. So some are more risk-averse than others. Some might be richer than others.
Doesn't really matter. And then the key exogenous parameter is just how expensive indexing is. Computers were expensive in 1980.
So it was kind of hard to run an index fund. And I think if I remember right from memory, Vanguard index funds went for 76 basis points a year or so. We all know that that has gotten cheap and that we get the stuff for free now, effectively for free anyways.
So the question is then what happens to stock market participation of these investors? And whether they hold individual stocks or the index fund instead, what happens to the asset prices? Just to simplify things, we say, look, these investors, they can only hold a small amount of individual stocks.
So what that would do is just force them to take on idiosyncratic risk if they wanted any equity exposure at all. It lets them hold the index fund, which gets rid of all the idiosyncratic risk. It's an idealized index fund, like in the textbook, not necessarily like in the real world.
But of course, they could also hold bonds. So the more risk-averse ones are going to hold a higher fraction of their portfolio in bonds or call that a savings account or a CD, whatever it might be. And the less risk-averse ones are going to hold a higher fraction in equities.
And now as you introduce index funds or just make them cheaper, more people are going to hold an index fund instead of individual equities, because the trade off goes, well, for just a small fee, I get a gigantic risk reduction. And others are going to shift more of their bond holdings into equities.
The logic being for a small fee, I get a much higher expected return and not that much more of a risk because idiosyncratic risk is taken out. None of what I'm saying right now should be surprising to anyone who has thought about these issues. This effect that I just described of people taking allocations out of their bond fund or their savings account into the equity market, that's a demand increase.
Again, if you by assumption, hold the supply of stocks fixed and increase the demand, it's got to be true that the stock price goes up. So that is just what happens in the model. The riskiness of the portfolios goes down, but the stock price goes up and it reduces the rate of return.
The fun result of this simplified model is actually every single one of the investors involved. Every single one is worse off when you have an index fund or when the index fund gets even cheaper, then if there was no index fund at all. So everybody likes that the index fund is there and buys it, they act optimally, but in equilibrium it's bad for everyone.
And the reason is that the risk reduction is precisely reflected in the increase in stock prices. And there's an externality. The externality is Ben's acquisitions of stocks drive up my stock price, no?
The more stocks he buys, the lower my expected rate of return is. As we all know, when there's an externality in a market equilibrium, people do too much of that stuff. So I'm being harmed by Ben's stock market purchases, and that's why it can be.
Again, I'll close this by saying it's a theoretical result. It's a possible result that the investor is actually worse off by the existence of an index fund. And then one can do variations of the model and say, okay, how robust is that result? What I just described, we held the rate of return on bonds constant.
What if the supply of bonds is constant, and actually as you shift out from your bond portfolio, the bond prices fall and the yields go up, rather than stay the same. And in variations they do, I can get into that, but I've been talking for a while here.
Ben Felix: What is the relationship with the fee? Is it a linear relationship where the fee goes down a basis point, or is it a different shaped relationship?
Martin Schmalz: Good question. I wish I knew a better answer. No, so to look for these interim results, we can actually solve that model analytically. But recalling the graphs, it looks kind of linear, but that's not a particularly great answer.
Ben Felix: Okay, interesting. I was just wondering if it's like, you know, if a Vanguard index fund is three basis points today, does it matter if it goes to two or are we basically at the limit of this effect now?
Martin Schmalz: I think we're probably at the limit of that effect, but that's not a very confident statement. I should really go back to that and figure it out.
Ben Felix: It's really interesting. It's also interesting that the effect in the short term, obviously this is theoretical and who knows where we are in the sort of timeline of the effect playing out, it would appear as if, assuming this theory is a good lens of reality, it would appear that we're at a point where asset prices have gone up, expected returns have gone down, but from the perspective of everyone participating in the market, unless they're thinking about expected returns, I guess, everyone's like, wow, this is great. Returns are really high.
Martin Schmalz: Indeed, indeed. And the co-author team, Bill Zame and I, discuss that quite a bit. He's been around for a few decades longer than I have.
We have lived that reality ourselves. Now, that's actually something the model can't really speak to because it's a static model, which would be the first critique one could leave against it because we live in a dynamic world. So it doesn't really inform these effects across generations.
And that's one of the expansions that we're working on to see, whether these welfare effects affect different generations differently and so forth. The comparison is between two alternative worlds, one in which index funds exist and one in which they didn't, it does not actually speak to the motivation of the fee coming down over the last 40 years and who benefited and who lost. But I mean, the intuition I certainly share that this was pretty great for those that bought it. It's just not that great for the people that are on the streets these days and vote for socialism.
Ben Felix: Right. You mentioned the welfare goes down for everyone. Are there any winners when the index fund enters the market?
Martin Schmalz: Yeah. So in this first simplified model, they're not, just every single investor is worse off. But that result is changed once you allow the bond prices to change as well.
So what happens is, again, the more risk-averse parts of the population, which also tend to be the less affluent, they have a larger share in a bond portfolio. Now, if you compare a world in which the bond prices are high versus low, meaning the yields are low versus high, as people shift more wealth into equity, as the yields go up. Now, who benefits from that?
Well, it's those people who get to buy the bonds for cheap and those are the highly risk-averse ones. So it turns out that in this variation of the model, there are a few winners from cheaper index funds, which is the people who hold the bonds, but they don't benefit because they hold a lot of index funds. They benefit because they make a killing on increased bond returns.
I don't think anybody should interpret this in terms of the time series of returns that we saw. It is really just to point out my conclusion of this paper is just, hey, we know a lot less than we thought. The thought process that we just went through is not really something that people think about when we try to evaluate the welfare effect of index funds.
And that starts to become important when one thinks of regulation of that or existing laws and antitrust laws that we're going to talk about in a moment. What is the optimal regulation of this sector? For that one, we should really kind of understand what the welfare effects are, even in such simple models, and we don't. And that's why we wrote that paper.
Cameron Passmore: Why is this a tragedy of the commons?
Martin Schmalz: So the tragedy of the commons really goes back to the point that if Ben buys more index funds, that imposes a negative externality on me because it drives down my returns, it drives up the price at which I have to buy the stocks. So it's really quite similar to the usual tragedy of the commons example.
Ben Felix: So interesting. It's good for each person in isolation, but when everybody does it, it's bad for everyone.
Cameron Passmore: Exactly.
Martin Schmalz: That's right. That's exactly what it is.
Ben Felix: So interesting. Do you have a sense of when does this start to matter? Because if index funds are small, it's probably not a big deal.
Martin Schmalz: You're again pushing me to think about this more quantitatively, as with your question about whether the effects are linear or not. And I mean, I honestly can't. I mean, this model is so stylized that it really just aims to point out there's this mechanism we don't properly understand.
We just qualitatively stated in the introduction of the paper, well, this probably didn't matter in 1976, but it seems like a good time to think about it now.
Ben Felix: Right. It does seem that way. I mean, index funds are big, no longer small.
Martin Schmalz: No longer small. At that point, it's just time to think about equilibrium effects, especially again, I'll go back to when people start thinking about regulating the sector, then you're regulating a gigantic part of the market. If you do that, there's going to be equilibrium effects of the regulation and how are you going to make predictions about the effects of your regulation, if you don't even have a model about such equilibrium effects.
So we just think that is a terribly understudied question that we are just trying to give a bit of a push to so people start thinking about it more seriously.
Ben Felix: Seems like it would be a tough thing to regulate too, when everyone recognizes the benefits, but the costs are so hard to see or to quantify.
Martin Schmalz: Yes. So I spent two years as a regulator in D.C. as a chief economist of the audit regulator, until a year and a half ago or so. There's a political economy, or the reality of regulation, which has some political motivations as well.
Let's say this carefully. And it doesn't exactly follow the Econ 501 idea that if there's a market failure, the benevolent dictator comes in and fixes it. But I do like to think that it's a nice benchmark to have to know what the right thing to do is.
Even before taking the political economy constraints into account, it's a really tough cookie to figure out what to do about it.
Ben Felix: How does indexing create common ownership of competing firms?
Martin Schmalz: There's an old idea from late 70s, people started talking about this and the early 80s, people started writing papers about it. Rubenstein and Yaari in 1983, and Julio Rotemberg in 1984, started writing papers that basically said, hey, this diversification thing that the finance people talk about, the Capital Asset Pricing Model and Markowitz portfolio theory, all that stuff. When you think about it, that's not really consistent with having competitive product markets.
And the theory goes like this. So clearly, again, if Martin owns all the firms in the economy on a given sector, then Martin is just a monopolist. He might be running a multi-brand strategy, but if you hold 100% of the shares, that's the same.
If Ben and Martin each own 50% of all the firms, then it doesn't really change anything. It's neither in Ben's nor in Martin's interest that the firms compete. So why would they?
We're going to find ways of making sure the managers don't or that they do what we want. But of course, if you take that to a theoretical extreme, nothing changes when there's 10 people that own all the firms and the firms still don't have an incentive to compete. Maybe you have a million people that each own 1 millionth of each firm.
That's called diversification. Then why would the firms compete? So that theory has been around for a while, for more than 40 years.
So then you can see that in theory, just diversification will cause common ownership of competitors. And again, in theory, threaten to reduce competition. Now in practice, that's not really what happens.
I tried to go out of my way for the last 10 years of scraping together all the SEC ownership records and constructing ownership structures of all U.S. publicly traded firms with it. And what you'll see is that a lot of common ownership in practice is not driven by indexing at all. It's driven by Bill Gates' family office owning a gigantic stake in one waste management company in America, and also in another.
There's Berkshire Hathaway owning 10, 15% in a whole bunch of banks, or occasionally in a bunch of airlines or insurance companies and so forth. And these entities would be way more diversified if they held shares in different industries as opposed to gigantic stakes in industry competitors. So that's a much bigger driver.
And even to the extent that it's our usual index fund providers, it's not the funds that create the common ownership. It's a centralization of all the funds' votes in one centralized corporate governance office and then effectively executes all the votes at once, until recently anyways. It's really the centralization of control, of corporate control, that drives common ownership.
It's not the indexing per se. I've been trying to get this message out for 10 years because people, I think, wrongly equate indexing with common ownership. So it's kind of dear to my heart to clean that up.
Ben Felix: I was thinking about this earlier. Do you think that because the big winners in indexing like Vanguard and BlackRock have these massive funds that are hard to compete with because costs are so low, does that itself drive concentration within those big asset managers?
Martin Schmalz: The short answer is yes. I think Vanguard is a particularly good example for that. There are scale effects.
I mean, if they want to offer that stuff for cheap for the benefit of me and you individually, if not an equilibrium, then of course they got to be large. But again, BlackRock is not an index fund. BlackRock is a collection of all kinds of funds, some of which are textbook type index funds and many others aren't.
So a lot of the centralization of corporate control one could also get rid of and Larry Fink himself pointed this out in Davos a few years ago by just delegating back voting to the individual fund managers. I'm not sure if that's a good idea. There's also scale effects in governing portfolio firms.
So depending on what one's precise theory of why that might be a bad thing for governance or for competition, that may or may not be a good idea to make active ownership less attractive to the large so-called index funds, which are not index funds.
Ben Felix: So it's really the concentration among large asset managers who oversee how funds vote the shares that they own. That's what causes these potential competition issues.
Martin Schmalz: Those in addition to the active stakes that I mentioned, there's also a whole bunch of activists on that bunch. There exists activist hedge funds just by shares and competitors are talking to them about, hey, why don't you merge and why don't we replace a few directors? They've gotten in trouble for that occasionally. Or of course in private markets, depending on who you talk to, private equity firms will tell you, oh, but that's our business model.
We call it industry specialization or a roll-up or whatever it might be. That is not necessarily a bad thing because maybe my dentist does become more efficient and offers greater, better services with less pain and lower costs if they have a more professionally run back office. Of course it might hinder competition if the same person sits on boards of competitors and that's what the FTC and the DOJ started enforcing really just in the last few years.
It's a very old law. People knew that this problem existed since almost a century ago. They just never bothered about enforcing it.
The management scholar, Peter Drucker, wrote a paper in the 1950s with the title of Pension Fund Socialism. He made a slightly different argument, but the notion that concentrating huge pools of capital that are controlled by a handful of people that this might threaten the capitalist system, that is not really a new idea, just the particular manifestation thereof and the empirical reality that is kind of new or really popped up in the last two decades.
Cameron Passmore: So interesting. So how concentrated is firm ownership today?
Martin Schmalz: In most firms, most large U.S. publicly traded firms, so the Big Three own well north of 20%, mostly approaching 30%. A whole bunch of stock is held in threes, in particular. It's less big elsewhere. Obviously there's exceptions. There exists publicly traded firms that have very large blocks of insiders that sometimes are called Elon Musk or Mark Zuckerberg or might even be controlled by individuals who don't own shares in their direct competitors.
So common ownership is really driven by the absence of such large block holders. The variation in common ownership across industries or firms is mostly driven by whether or not you have such a large non-diversified block holder at the top of the shareholder register or not. But this is more of the exception than the rule.
You get that in a few industries and then just in one or two firms per the industry, but not in others.
Ben Felix: You've done a lot of work on this. What does the evidence show about the effect of concentrated ownership on competition and then ultimately on consumers?
Martin Schmalz: The broad strokes answer is that there is quite a bit of evidence that product prices go up when the same investors own more of the competitors. And this is not a time series statement or a statement across different industries, which would be difficult to identify. It's a statement that started with a paper on the U.S. airlines industry. So what we showed there is that you look at root level prices. How much does it cost to fly from New York to San Francisco? And how much does it cost to fly from New York to Boston? Those are two different markets. It's a different product. So there's different markets.
And the airlines that fly that route are different airlines and they have different owners. So they have different degrees of common ownership. What we see is that in those markets where common ownership goes up, ticket prices go up in those markets where common ownership goes down, for example, because a large, undiversified investor buys a huge stake in one of the competitors.
That's why the prices go down. If you're an empirical finance, empirical corporate finance corner, this description triggers a mechanism for thinking about what all the endogeneity problems are and reasons why this might not be causal, but just a correlation. So what we did in that paper is using BlackRock's acquisition of Barclays Global Investors in 2009, which presumably didn't happen because of U.S. airline ticket prices in New York to Boston and San Francisco that would be observed. But of course, it actually did change the ownership structure of U.S. airlines as a side effect. So what we do is look at the portfolios of these airlines a year before the merger or the acquisition. And say, if hypothetically, you combine these portfolios, how would the ownership structure of U.S. airlines change? And then we use this hypothetical increase, which is correlated with the true change in ownership as a shock to ownership.
As if you gave a black pill versus a white pill to different U.S. airline routes, it turns out you can predict years into the future in which U.S. airline routes prices increase more than in others based on that acquisition. It's a bit wild, as one famous economist said, seeing these results. But of course, it perfectly corresponds with the theory.
So that's one piece of evidence that people have replicated this in other industries with different methods and so forth. But really, the interesting question is whether this happens due to the 1980s style theory that the investors basically act like monopolists, and they just extract higher margins, which might explain why their capital share went up in the macro economy, while the labor share went down and all these good things that we see in the macro data, or whether it might be for a completely different and much more boring story. And a boring story goes like this. So I'll call them index funds, although they're not.
The index funds are really just lazy owners. Yes, they have these corporate governance teams, but really, I mean, honestly, compared to an activist, they don't really do anything. And what happens is that it just weakens monitoring of the management team.
Oh, when Richard Branson shows up at whoever ran Virgin America, there's a very direct link and Richard Branson talks about, oh, you're going to buy new airplanes, extract market shares, he puts a bit on lipstick, shows up as a flight attendant, you really try to steal market share from competitors. Now, I've never seen Warren Buffett or Larry Fink put on lipstick and try to help Delta win market share from United. And the next day, show up United and try to help them steal market share from Delta.
I mean, that would be absurd for many reasons. One reason it's kind of absurd to think of Warren Buffett was lipstick, but the other one is it's absurd to think that you would help two of your portfolio companies find ways of stealing market share of each other. And that is an important point.
The important point is this theory here is not about increased incentives to collude. The theory is not Warren Buffett calls up the airlines and tells them to collude. The theory is, by contrast, to a large, undiversified owner, he does not have incentives to push the firms to compete particularly aggressively. Whoever has read Adam Smith, happy 250th anniversary. Anyways, The Wealth of Nations and all that good stuff.
The whole theory of capitalism relies on the idea that the baker on one side of the street sees the prices and the bread of the baker on the other side of the street and tries to either outcompete them on quality or price for entirely selfish motives. And the result of all these selfish motives leads to the wealth of nations. That's the whole idea of capitalism.
So the point is just that if the two bakers on the two sides of the street own 50% of each other's bakery, then the competitive incentives, they just go away. It's about the absence of incentive to compete and it goes to an incentive to collude. So that's a very different theory of reductions in competition that calls for different evidence. It also calls for different policies.
If the problem is that they don't really do anything, in corporate governance to make managers to reduce costs or increase innovation, you might come up with very, very different policy implications. And then your main worry is that they call up competitors and tell them to collude. So that's why it's important.
And that's where really much of the recent literature has gone, to try to distinguish between these different theories of why prices are higher when there's all this common ownership around.
Ben Felix: It was 1776 that The Wealth of Nations came out. It is 250 years. There's like an anti-competitive cost imposed on consumers from common ownership.
Does any of that cost come back as a benefit to the air quotes "index investors/lazy investors" through the ownership of those companies?
Martin Schmalz: At least in the theory that common ownership comes with higher product prices because it comes with higher margins, you might say, hey, look, the whole thing is a wash. The three of us are the only investors in the airlines. We are also the only customers.
It's the right-pocket, left-pocket kind of thing. Turns out Joe Farrell, Berkeley professor wrote a paper about this in 1985 at Bell Labs. It has the most beautiful abstract in all of economics, according to me. Nobody seems to share that view. The abstract goes like this. If each household owns the same fraction of a firm as its share of consumption, then shareholders unanimously want marginal cost pricing.
It's exactly the intuition that look, we don't really care. All we want is that the firm prices effectively. We maximize social welfare as in Econ 101.
Second sentence of the abstract. Otherwise, profits are overemphasized relative to consumer surplus. So in other words, if you have inequality and some people do all the owning and other people do the consuming, well, then the owners are going to overemphasize profits, relative to consumption.
In theory, yes, if we lived in a world without inequality, but given the world we live in, which is really kind of consumers versus capitalists, that's not a political statement. That's an empirical statement. This is really about extracting rents from one part of society and redistributing elsewhere.
I think for all practical matters, the answer is no. The poor people like you and me, relatively poor compared to very rich people. We actually probably pay way more in increased product prices than we get back through our index portfolios from such reductions in competition, just because the wealth distribution is super unbelievably skewed.
Ben Felix: Yeah, that's really interesting. You gave the example of the dentist being rolled up by private equity. I guess we could apply similar thinking there.
Martin Schmalz: Yes, we just don't have a lot of data on it. So the reason one does his research on public markets is that's where the data is. If there was a place that would be concerned about common ownership and product markets, it would probably be first in private markets rather than in public ones, which is one more reason not to confound common ownership and indexing.
They can leave our index funds alone for quite a while. There's lower hanging fruits.
Ben Felix: We went from the kind of equilibrium effects of index funds to the effect on common ownership, which we established is not necessarily an index fund issue, but I just want to come back to the equilibrium effects. Can you talk about how your model differs from reality?
Martin Schmalz: That's actually a great way of closing the circle here. When you asked me about how the model was set up, one of the things I said is the firms have a fixed profit or dividend process. So in other words, the ownership of the firms in that model does not affect how efficiently they run, how they set product prices and all that stuff.
So in that model we previously discussed, these empirical effects I just described are not present there at all. Okay, so that's one way it differs from reality. There's all kinds of other deviations from reality.
There's no other funds. There's no active funds. There's all kinds of simplifications, again, just to illustrate the point that we know less than we think.
But the other point it illustrates, which we didn't talk about is this. It might just be that the effects the model predicts, the 1980s-style industrial organization model predicts, is precisely the opposite of what a model predicts that has a consumer surplus included. So let me try to explain this.
In the 1980s-style models, common ownership or diversification is a good thing for investors because the well-known reasons, reduces risk and all that good stuff, and redistributes rents from consumers to investors. So it's a good thing for investors, but it's a bad thing for consumers. Shift back to the equilibrium indexing model we discussed.
There, indexing is bad for investors and might be good for consumers. And here's why. Remember, the lower rates of return, the lower expected returns for investors, that just means lower cost of capital for the firms.
But if the corporates have lower cost of capital, that means they have a lower cost of production. If they have a lower cost of production, they're going to produce more output. Somebody's going to eat all that output.
That's the consumers. The fun ta-da moment is you realize once you endogenize the asset prices into these models, you might get that indexing is bad for investors and good for consumers, which is exactly the opposite of the intuition that comes out of these models in the 1980s and that a lot of the policy discussion is based on. And I cannot emphasize enough, nobody should believe that model that we wrote down.
The point is just, we know a lot less than we think. And if you think about regulating the entire industry by really making market-changing regulations or even prohibiting certain types of ownership structures or disincentivizing them, you're going to change an equilibrium and changing an equilibrium without having an equilibrium model is a bit of a gutsy thing to do. Again, from the practitioner/policymaker standpoint, I mean, people do that all the time.
People make regulations without understanding the equilibrium effects all the time. But this is just a bit of a word of caution to say, you really want to think about this carefully before you pull out the sledgehammer here.
Cameron Passmore: And how concerned do you think index investors should be about your findings?
Martin Schmalz: I think mostly not. So at some point, BlackRock disclosed in their investor filings that the policy debate based on this paper is a risk to their business, which triggered a bit of an unpleasant period in my life. But I've emphasized a few times here.
I don't think that we know that there are any competitive effects that have much to do with indexing, per se, at all. I don't think index investors should spend too much time staying awake at night thinking about these effects. Policymakers should. But index investors, I'm not sure that they have much to worry about either.
Ben Felix: Was it the competition paper or the equilibrium paper that caused an unpleasant period in your life?
Martin Schmalz: Oh, the competition paper.
Ben Felix: Okay.
Martin Schmalz: The equilibrium paper, that is newer. It was the competition paper. It was a Harvard Law School professor called Einer Elhauge who wrote a paper about our airlines paper and explained which existing antitrust laws might be applicable to that situation.
Not a policy discussion about what we should change, just what the existing law really says about this. And so one short summary of that is that one thing of filing obligations, there's this Hart-Scott-Rodino Act. If you buy shares in competitors and don't notify the antitrust authorities, that can get very expensive very quickly. That happened to one of these active hedge funds that bought shares in competitors and did not notify the authorities.
The second one is the Sherman Antitrust Act that prohibits us from fixing prices, collusion. We just spent half an hour talking about that. This is not what this is about. Let's forget about this one.
But there's also the Clayton Antitrust act that has Section 8 that says you can't sit on the boards of two competitors. And that's the one that the authorities started to enforce in the past few years. And there's Section 7 which says you cannot acquire an asset or a part thereof, for example, a share of a company.
If the effect of the acquisition was to substantially lessen competition. The interesting thing in that the sentence is it doesn't say how you bring about the lessening of competition, whether you do it by whispering to the CEO or by voting your shares or whatever it might be. There's nuances to that in the footnotes.
I'm not a lawyer, I should also say that. But the thrust of the argument is you buy an asset, it affects competition, the acquisition is illegal. Remember how we use BlackRock's acquisition of BGI as a shock, so you can see how that would make some people a bit defensive about it.
Ben Felix: Yeah, I can see how that would get uncomfortable. You mentioned policy. What kind of policies could be looked at for either one of these issues, either the equilibrium effects or competition?
Martin Schmalz: Enforcing existing policy would basically go market by market. Find yourself a market in which there are measurable effects of common ownership on prices and you undo the acquisitions, or ask for divestitures, and so forth. And the authorities have been doing that.
They've been starting to measure ownership in M&A transactions to see whether that changes their analysis and so forth. That is just going about their business as usual. But if you want to think of system-wide changes, then it gets more interesting.
The two classes of proposals people have made, there are more in fairness, but two that I'll speak about here is one is you basically prohibit common ownership, you say you can only hold one firm per industry, at least if you're holding more than one percent. And the other idea is, well, you can hold as many competitors as you want, but then you can't vote your shares. You just take voting rights away from index funds, mostly.
And the argument goes like, look, they don't really want them anyways. They really only vote them because the SEC told them to 20 years ago and told them that this is part of their fiduciary duty. And for the longest time, I thought that this is a really dumb idea, because if you take the voting rights away from the largest shareholders of companies, then you're creating an unbelievable agency problem.
And if the 73rd largest shareholder suddenly effectively controls a firm, that shareholder is going to get very funny ideas. So my funny idea would be, I'm going to become an art painter and sell my art to the company that I control. That's called tunneling.
I mean, it's just a classical principal-agent conflict that you create with that. Here's where my thinking is wrong. My thinking is wrong because the ownership structure would change, because once you become the largest and the controlling shareholder by being the 73rd largest, the two of you would also get funny ideas and start buying more shares in these firms to gain more influence.
So the entire equilibrium ownership structure of the economy would change once you impose rules like that. And precisely how, and what the answer is, we have absolutely not the faintest idea. Nothing, absolutely nothing in the literature, because in these pretty finance models we have, Markowitz and so forth, we assume away any problems with competition. Markowitz and returns, they fall from the sky, then it says go form a portfolio, then you do your diversification thing and that's it.
It's just assumed away that the ownership structure would affect the way the firms compete and how high the profits are and therefore how high the stock prices would be. You can see that in reality, of course, is a gigantic amount of feedback going on. We have no models that inform that.
And that is basically what I spent the last few years of my life trying to develop and will spend the next few years trying to work out. That we haven't even a faint idea of what would happen if we implemented some of these policy changes.
Ben Felix: Sounds like the main takeaway is we probably know less than we think and people who currently invest in index funds probably shouldn't worry, but people at the policy level should maybe think a little harder.
Martin Schmalz: Indeed, indeed, you should not take these models seriously, I discussed so far. But if you did, you'd say, oh, wait, but there's nothing to fix because remember, indexing is bad for investors and good for consumers. So to the extent you want to fix consumer welfare, everything is fine. Again, you should not believe that.
But the point is just the intellectual provocation that this is an easily thinkable model that one could live in in order to figure out what the optimal interventions are. You really want to have better models than the ones we wrote down so far already.
Ben Felix: I guess one implication for index investors, it's not like you should not invest in index funds, which I don't think is the takeaway at all. One practical consideration could be to incorporate lower expected returns.
Martin Schmalz: Yes, I don't usually make predictions, but that seems a sensible thing to do a irrespective of the entire theory that we just laid out for high P/E ratios and other stuff that you've discussed in earlier podcasts.
Ben Felix: True. You don't even need your model to expect lower returns right now, I guess.
Martin Schmalz: Exactly.
Ben Felix: That was all super interesting. I want to move on to the broad theme of the next set of questions, which is why don't wealthy people just invest in index funds?
Martin Schmalz: The reason I chuckle is because a few months ago, I sat in an airplane next to a wealth manager of a very well-known private bank who told me this verbatim. He was like, I don't understand why my clients don't just open a brokerage account and buy a bunch of ETFs. Now, let's start first with a factual observation, which is that they don't.
There's not great data, but some data that many families, dynasties lose gigantic amounts of capital within a generation or two. And at the same time, you and I know, and the listeners of this podcast know that if you costlessly held a diversified portfolio, you could not possibly lose money over the last few decades or even centuries, although it was hard to do it costlessly. So what I conclude from that is that those people who lost their money did not costlessly hold a diversified portfolio.
I know that's not particularly advanced logic, but I think it's kind of useful because it tells you that what these people must have done is either not diversify, or they had way too high costs of running a portfolio. So that's what I mean when I teach. I call them the cookie monsters of wealth destruction. So you say, why don't people just index?
We can talk about this, but the first observation is that clearly they don't. Otherwise, they couldn't be losing all that wealth.
Ben Felix: You mentioned the cookie monsters of wealth destruction. I think you have three. What are they?
Martin Schmalz: All right. So I talked about the third one. So the third one is just behavioral mistakes.
We've talked about this before, people tend to trade way too much, which costs trading costs. They trade at the wrong times and they trade when volatility goes up and then buy back the stock when volatility is down and the prices are up again. So they sell low and buy high and that turns out not to be a wealth creation strategy.
Lots of behavioral mistakes might be the third cookie monster. I think maybe there's a fourth, which is fraud. There's a whole bunch of large family offices that lost a chunk of their wealth to fraudsters.
I say that's just half of one because if they were diversified, it wouldn't matter. It turns out I was a shareholder in Wirecard.
Ben Felix: Oh, wow.
Martin Schmalz: I think because I hold index funds, so presumably you were too, but we didn't notice. So my point is fraud is not really a problem in a diversified portfolio. It's just a problem if you invest half of your wealth with a fraudster and then it disappears.
So that's why I don't really think of that as a separate cookie monster, but in reality, it is one.
Cameron Passmore: How much does volatility matter to long-term wealth?
Martin Schmalz: Also, here, I don't have anything new to invent. There's this thing called volatility drag to recover from a 50% loss. You need a 100% gain and all this good stuff. And that's why it's so important to diversify.
I sometimes feel like I look at my MBA students, I think that this diversification concept we preach is some hobby of finance professors, but it's not. No, it's just that's what you need to create long-term wealth and to compound. So I think we need to explain that better.
So that's one reason to diversify the wealth. The other one being the skewness part, right? So you had Henry Bessembinder on, the right skew of stocks drives the entire equity risk premium.
Jack Bogle said that as well, "don't look for the needle in a haystack just buy the haystack." I don't recall if that came up on this podcast before, but it can't be emphasized enough. So there's lots of reasons to want to diversify broadly.
One question for finance professors that are looking for research topics would be, is it also true in private markets? I would guess that it's much more important in private markets. The right skew.
But the reason that matters is because it's really hard to hold a diversified private asset portfolio. And if diversification is important because of the needle in the haystack problem, and that would point to that, it's even more important in private markets to hold a diversified portfolio. But that's just conjecture and hypothesis that somebody should work out.
Ben Felix: I think that's right. I mean, Bessembinder also has a paper on mutual funds skewness and finds kind of the same thing, that mutual fund returns are skewed. And I think venture capital returns are even more skewed.
I'm not sure where private equity buyouts fit. It would seem sensible to infer that skewness in at least the venture capital market is even more extreme than in public markets.
Martin Schmalz: Indeed, indeed, yes.
Ben Felix: You talked about the private wealth guy in the airplane who wasn't sure why his clients don't just invest in index funds. We kind of talked a little bit about the fact that they don't. But why do you think?
I mean, you talk to people, you talk to wealthy people. Why are wealthy asset owners reluctant to just buy index funds?
Martin Schmalz: The main reason is probably because that's not how they created it. And they have that unexamined intuition that the methods and intuitions that created the wealth are also suitable to preserve it. The anecdote I like to tell with some trepidation of why that's a silly idea is if you run across a lottery winner who became rich by buying a lottery ticket, I think everybody understands that continuing to buy lottery tickets is not a great way of preserving the wealth, although it was absolutely a way of maximizing the probability of becoming rich.
So I'm saying this with trepidation because obviously there's more than luck that contributes to entrepreneurial success. So I don't want to minimize all the other skills that entrepreneurs have in creating wealth. But it just drives home the logical point that wealth creation and preservation are different disciplines.
By my own lights, I just think that entrepreneurs have personality traits that make them successful as entrepreneurs that quite systematically kill them as investors. And I should preface that this is not hard science here. This is really just me making casual observations about the world.
But an entrepreneur makes handshake agreements, trusts a counterparty. That's great. In finance, you better read the contract of the product you bought or run a due diligence on your private market counterparty.
Trust is not a great way of running governance. Courage or confidence, maybe even overconfidence, is a great trait for an entrepreneur. As an investor, you probably want to be well calibrated and not underestimate risks, but properly assess, run risk management strategies and so forth.
You probably don't want to make your investment decisions based on intuition. You probably want to do it based on analysis, completely antithetical to not all, but many entrepreneurial success stories, or an intuition that you want to actively manage assets and have control over them. Great trait for an entrepreneur.
They cannot possibly lean back and buy an index fund and participate in the success and effort of others. Or just the ambition to create wealth is kind of bad. If you think that you have to create alpha to run a family office or preserve your wealth, well, then you take on the risk of having quite negative alpha, in fact, because there's someone on the other side of the trade.
Even just the ambition to create wealth as opposed to participate in the overall wealth creation, I think, is just antithetical to the personalities of the people who created the wealth. That is very hard to shake off. Sometimes it just gets shaken off from generation to generation, really.
But yeah, I guess another reason is, and perhaps paradoxically, people just are really bad at stomaching volatility. I say that's a bit paradoxical because entrepreneurs took on this unbelievable amount of idiosyncratic risk that is more risky than holding all your wealth in Tesla, or whatever the particular individual stock is. And at the same time, when an ETF goes down 20% and a line wiggles on a chart, they scream, "sell," and make all these trading mistakes.
I don't find this funny, it's like super painful to me to watch that stuff. But I think it's just a reality that people get scared when volatility goes up. The intuition part comes in, unbridled governance, the patriarch makes investment decisions the same way they did in the business, react very quickly.
And that's exactly what then kills them as an investor. A lot of the wealth gets destroyed that they spent many years trading.
Cameron Passmore: What is horizon-dependent risk aversion?
Martin Schmalz: Oo-la-la. So that is a while ago. So almost 20 years ago in grad school, my co-author Thomas Eisenbach and I came up with this term because we were wondering how to describe the behavior of an investor who's more risk-averse to short-term risks than to long-term risks.
Let's reflect and step back a bit. In all the little econ models you find in textbooks, you might have time-separable utility functions, you know, utility that evaluates today's risk and tomorrow's risk and next month's risk. All these little utility functions, they have the same shape.
There's the same risk aversion. That seems like a restrictive assumption. So if you read the psychology literature, you'll find quite a bit of evidence that people just get scared of stuff.
And to make this slightly more intuitive, you might think that going bungee jumping is a great idea because, you know, it seems like a good life experience to have or something to brag about with your friends. But once you stand on the brink and you're supposed to jump, then you feel much less of an inclination to jump. People chicken out from stuff.
So the closer, the more proximate the resolution comes, the more scared people get. I mean, take stage fright. I don't know if the two of you are musicians.
Ben Felix: No.
Martin Schmalz: Stage fright is a thing. Musicians take beta blockers or some people take alcohol.
There's a scene in A Beautiful Mind of John Nash standing in the D-Bar at Princeton and drinking a few beers to have more courage to talk to members of the opposite gender. Obviously, it's very intuitive to people that, of course, people get scared of stuff, they chicken out and they're kind of aware of it to an extent that they even start coming up with devices to change their future selves' risk aversion. They start playing games against their future selves.
So anyways, we had lots of fun in grad school thinking about how agents might behave and how assets might be priced. In fact, when people have horizon-dependent risk aversion, rather than these normal utility functions we set up in grad school...
Ben Felix: How does that concept, horizon-dependent risk aversion, explain that phenomenon of investors selling assets when volatility shows up?
Martin Schmalz: When you think of an increase in volatility, just as a risk that becomes more imminent, people knew it was going to come at some point. But when it's there in front of your face and you open your Bloomberg and or FT and the screen is red, that triggers this feeling of, we call it anxiety in one of our papers, then they just behave in more risk-averse ways. So you shift out of your equity allocation into a bond allocation and once the risk ebbs a bit and the anxiety is gone, you go like, oh no, but wait, I read that equity has higher expected returns, and let me shift back. That seems very intuitive and that's kind of the point.
It's not that people make these rational decisions in these periods of stress, they just trade out. It is actually quite a direct explanation for that phenomenon.
Ben Felix: Have you guys ever gone bungee jumping?
Martin Schmalz: I have not.
Ben Felix: Have you Cameron?
Cameron Passmore: No.
Martin Schmalz: But I watch lots of videos of people going bungee jumping for research purposes. One fun one involves a guy standing on the edge of the cliff with his girlfriend and pushing her down because she refuses to jump. It raises very, very interesting questions about paternalism and whether that's a good thing or not.
So it raises all these interesting questions, including whether governments should encourage their citizens to take on risks that they would otherwise be unprepared to take.
Ben Felix: That's interesting.
Martin Schmalz: Think about sovereign wealth funds and stuff. I'm still kind of puzzled about countries like Norway at the same time taxing their citizens and saving for them. It's kind of interesting.
Ben Felix: I've done bungee jumping once and it was exactly as you described. It seemed like a good idea. And then you're standing on the edge of this platform and they actually tell you, or they ask you, this place didn't force you to jump, but they ask if you would like to pre-commit to jumping, where they're going to count down from three and if you don't jump, they're going to push you.
Martin Schmalz: Really? This is so interesting.
Ben Felix: It was interesting. I agreed to that pre-commitment. I did jump in the end. I didn't need to be pushed. It was terrifying though.
Cameron Passmore: Wow.
Ben Felix: I will never do it again. Once was enough.
Martin Schmalz: That is so fun to here. I didn't know that existed. That must certainly depend on the legal system you're in, whether that's a thing that they can legally do.
Ben Felix: Yeah.
Martin Schmalz: There's more examples of that. In the 1950s and 60s, if I recall, there used to be vending machines at airports right next to the gate at which you could buy life insurance. For the case that you died on this particular flight.
Ben Felix: Wow.
Martin Schmalz: And of course, the premiums were super high-margin products. And I think this originated in Japan, but I don't piece these things together well anymore. At some point that got prohibited because there's some regulation that makes you need to have a salesman present to sell insurance or whatever it might be.
The need for humans to want insurance at the supermarket cashier, you buy yourself new speakers, a new TV, whatever. All these insurance products when people make it very palpable at the rental car checkout counter, all these super high-margin insurances, they tend to be sold in situations where people stand on the brink before jumping, metaphorically speaking.
Cameron Passmore: So what does horizon-dependent risk aversion imply about paying for delegated investment management?
Martin Schmalz: It's kind of the same as in Ben's bungee jumping experience. For sophisticated investors, by sophisticated, that's a technical term to say, you know how you'll behave in the future, as opposed to being taken by surprise by or chickening out, might have a demand for commitment. As a demand for commitment, somebody's going to supply the commitment.
What it implies is that there should be a market for people who take risk on behalf of others, investment risk in particular. So you say you have this entrepreneur who is great at taking on idiosyncratic risk in completely illiquid markets, but just cannot for the life of him or herself hold a diversified ETF through a market cycle. So that person should have a demand for commitment to delegate holding that risk through the market cycle by someone else.
And for a small fee, I would be perfectly willing to do that. Even if I have absolutely no skill at beating the market, or even if I have negative skill, I might be producing negative alpha after fees, but that's still better than not holding any equities at all. The investor might just say, look, let's be honest, I'm not going to be able to hold the equity, but I might delegate it to someone else who will just not give the money back to me when I call them. Matt Levine at Bloomberg makes fun of brokers' phone lines not working during periods of high volatility, which is a great service to investors. But of course, you could think more about this. Cliff Asness calls it volatility laundering when people just make private market investments, not because they believe that they produce alpha, vis-a-vis the stock market, but because you can't sell them when volatility is high.
So you might just have a commitment to delegate it, investment management. And maybe that theory provides an explanation for why people invest with asset managers that have gates or will just not give you your money back while you're nervous, but only three months later, at which point, you probably don't want the money back.
And that's great. Even if these investment managers underperform the market, and that's what the horizon-dependent risk aversion implies about paying for delegated, investment management.
Ben Felix: Yeah, it's interesting. So people are better off because they're able to take more risk, even though they're paying a fee. So even if we can look at it and say, well, you would have been better off without the fee, it's like, well, no, they would actually have been worse off without the risk.
Martin Schmalz: Exactly. It's the traditional economist way of comparing them to a benchmark of if you just had held the risk yourself, it would be better off. But that might just not be a benchmark that human beings, or some human beings, can actually implement.
Ben Felix: Yeah, the counterfactual is a different portfolio entirely.
Martin Schmalz: That's exactly it, Ben.
Ben Felix: Do you think family offices are smart money?
Martin Schmalz: Okay, look. That's a bit of a broad question. And there are some extremely sophisticated family offices out there, and they definitely qualify as smart money.
But it's definitely true that there's a few unsophisticated ones out there as well. And what's also true is that they're not perceived by many market presidents as being smart money. And that's where the propensity to fall victim to fraud comes in.
Obviously, there's an entire industry out there that makes a lot of money by convincing people that they're in a privileged position to be allowed to invest in their fund and all these good things. People just have to guard the human instincts of falling for these things. And yeah, so a certain amount of humility, I think, is what does well for investors; mostly thinking that if someone offers them an investment opportunity, that's probably because nobody else wanted to invest at the same terms.
Ben Felix: Do we even have to go as far as fraud or do you think family offices get preyed upon by other whatever people selling financial products?
Martin Schmalz: Absolutely. We definitely don't have to go to fraud. I sometimes go to family office conferences to experience what kind of information flow family offices are exposed to.
It's just the usual tricks of triggering people's worst instincts. For example, one presentation I see is the fund manager effectively showing them statistics on how active fund managers underperform the index, or most of them do. How over longer time horizons, whatever it was, 10 years, 95% of them underperform the passive portfolio.
So far, we all agree. Here comes the plot twist. The plot twist goes, and if you pay close attention in the next 20 minutes, I'm going to show you how to be in the top 5%.
So this is just effectively just selling lottery tickets. You prime people to want to beat the market even if it's extremely improbable, so that's extremely appealing to human beings. And unless you think in terms of probability distributions and have an analytical mind, it's very hard to guard against it.
I have the same bad instincts as the next guy. I just try not to act on them. You definitely don't have to go to fraud.
It's just offering people what they want to hear and what most people want to hear is not actually good for them in terms of investment.
Ben Felix: Forget about the base rates. I've got a product to sell you.
Martin Schmalz: That's right. Don't ask about fees. In that presentation, by the way, there was not an inkling of evidence that they actually outperformed the index.
That doesn't matter. That's just about the looking sophisticated with Greek letters and all that.
Ben Felix: That's too funny.
Cameron Passmore: So what do you think, then, is the best setup for large wealth owners?
Martin Schmalz: I think that mostly just depends on the goals. I teach a class at Oxford that starts with the premise that surely at least part of your objective is to preserve the wealth for the next generation. So let's study what you have to do for that.
How does diversification work? How do you reduce the costs of running your portfolio and so forth? And after a day of that, you see lots of bored faces and they look at you in the eye and say, but then that doesn't feel purposeful.
And what's the point of it all and all this stuff? And I think that's actually the most important thing family offices should do before they start designing investment strategies.
They need to figure out what is actually the goal. What are the individual's goals of this process? If it's wealth preservation, that's great.
Then you follow one strategy and if the goal is impact investing, even if we can't measure the impact, then that's what they should do. But I think there's often a huge misalignment between what the goals are and whatnot. So one popular strategy is just to have one bucket that's for the wealth preservation and another bucket that is for all the non-financial goals and then putting a governance structure on top that makes sure that money doesn't flow between the buckets and control the lane.
A good setup is one that fits the goals and a bad setup is the one that doesn't. That sounds like a perfectly subjective thing, but I do think there's some objectively bad things out there. Let's take a small detour on costs.
We started this whole segment by talking about how people don't fully diversify portfolios at low cost. So let's talk about why that is important. We talked about why it also is important.
Cost, I think, and the people underestimate as well. So a few people in every seminar know about a percent know that if you make a 7.2% return per year, your wealth doubles in 10 years. That's just this rule of thumb for how exponential growth works.
Half of those know that that implies that after 40 years, that's called that a generation, your wealth is supposed to be 16 times what you started with. So you start with a billion after 40 years, you'd have 16 billion if you're compounded at 7.2%. Now here's the question that one cannot quite as easily answer with the rule of thumb, which is if you have a 2% cost per year, since I have 7.2% return, you make just 5.2%. How much do you now have after 40 years? And the two of you probably have a good intuition about this. And the answer is it's less than half. You have 7. something instead of 16.
So the point is a 2% cost per year eats half of your wealth in a generation, not half of your returns, half of your wealth. Now what are these costs? I mean, there can be many things.
Of course, they can be asset management fees, custodian fees. I've got no swipe at them, but of course they can also be withholding taxes. They can be the cost of running your structure, the lawyers, the accountant, and God knows what, your due diligence for the private investments.
Once you add these things up, you see that you're very, very quickly, way above 2% a year if you don't pay attention, especially for smaller family offices. So anyways, all of that was going to be the long answer to the question of what's a bad setup. I mean, a universally bad setup is one that has just way too high costs for no particularly good reason.
And I think that's an area people underestimate a lot. There's also some universally bad governance structures. My favorite one of those is probably the one where the patriarch goes and says, I want my kids to get along.
Therefore, I shall impose that all decisions get made in consensus. That never works. The reason that never works is you're giving 100% of the power to that kid that blocks all decisions, even if in substance everyone agrees.
I mean, I would start asking for an extra kickback if I also agree. There's always going to be a last person in the row. So you're creating a structure that only works when there's consensus, but you're disincentivizing consensus.
Well, people should be doing this, of course, creating structures that also work when there's no consensus, but that incentivize consensus. No, and it's very simple. You just add to your charter or to your governance structure.
You say the kids make decisions in consensus, but if they fail to reach consensus, then all the decision making power for a year goes to the chairman of the board, some external party, or the nuclear option, then everybody has the right to trigger an auction for the other one's shares or something. People will work very hard to prevent that outcome and losing control. So this way you incentivize consensus.
Anyways, there's a few universally bad ways of doing investments or structuring the asset allocation by not making it commensurate to the size of the family office. And there's a few universally bad ways of structuring governance. It's just very personal. It depends on what the goals are of the family.
Ben Felix: What about for less wealthy families, I guess, who don't have enough wealth to set up and cover the infrastructure costs of a family office? What do you think is the best set up for them?
Martin Schmalz: To close the circle, probably just index, but that's just to recap a bit of why we come to the conclusions so quickly. We emphasize the importance of diversification. It's kind of hard to diversify a private market portfolio.
My favorite example of that is probably real estate. I teach real estate at Oxford. Every year, half of my class is full of people who don't work in real estate, but who figure my grandma told me that real estate is a good inflation hedge.
And therefore, in their private portfolio, after they bought their own house, they then buy a bunch more houses to rent them out. That is sometimes a good idea. And sometimes it's not a good idea.
But ex ante, it's almost certainly a bad idea because you're way overweight in the language of asset managers, you're way overweight. Two assets that have a minuscule fraction of the overall market portfolio; it will be very surprising if that portfolio, over long horizons, would perform nearly as well as a diversified one. It's basically impossible.
So family offices make the same mistakes as individual investors. They invest in asset classes that they have no business being in and just because they can't diversify effectively in those. So real estate being one of them, lots of private markets, being another one, we mentioned due diligence for your private market investments.
Well, that's a fixed cost. So that has to spread over lots of capital to make sense. They need to still earn these excess returns that you're hoping to get in private markets.
But then if you spread this over a huge amount of capital in this one investment, it's very hard to diversify again. So you have to be really, really rich in order to be able to diversify in a private portfolio. So for investors who are not large enough for that, they'd be better off just holding liquid investments and leaving all this illiquid stuff to really, really, the largest investors.
Ben Felix: Makes sense. We've spent the last hour or so talking about how to think like an economist on various issues. Why does thinking like an economist cause unhappiness?
Martin Schmalz: You're referring to this semi-serious blog post I wrote, I think it was during the pandemic, but a while ago, and I think I titled it something like, Yoga for Economists or something like that. The argument there is that people who study economics end up applying that to life as well.
I think that's probably a bad idea, both based on my self-observations, but also based on, not just what yogis have taught, but a whole lot of Eastern philosophies have taught over a few centuries. Let's do a few examples of how thinking like an economist is basically opposite of what yogis teach us, we should be doing to be happy. One of the things we learn in Econ 101 is there's a thing called externalities.
And if there's an unpriced externality, I could pollute the river. Then the profit or value maximizing, the utility maximizing thing to do, is just to pollute the river. A yogi would look at this and say, wait, the first person you're harming is yourself because you'll just not feel great about having harmed other people, which is basically the opposite of how economists think about the issue.
That doesn't make economic thinking wrong. It is the right way to think about economics, but not about your personal happiness. Or the other example is thinking counterfactuals.
That's probably more important. People are happiest when they are in the moment. They focus on what they're doing right now, no matter what the thing is. What economists say is like, no, no, don't be happy with what you're doing.
Think about what you could be doing instead and what are the opportunity costs of playing basketball or playing the piano or hanging out with your friends right now. You could be doing work and making money. I mean, I don't need to explain to any human being listening here that this is probably not a happiness generating thought to have.
But it is what we teach in econ classes. And again, that doesn't make econ wrong. It just makes it not a recipe for happiness.
It's a recipe for maximizing whatever the econ teacher's trying to maximize. And I guess the more general point is that the focus is on outcomes rather than on the process. So what yogis and Buddhists and so teach you to do is to focus on the process of being and breathing and all these good things as opposed to whatever the paycheck is at the end of the month.
And I think that matters a lot especially in this day and age when AI is taking a lot of the process away. So we've all seen loud protests by mathematicians quitting their jobs because suddenly it became so efficient to do proofs. So that is, on the face of it, kind of puzzling.
You say, your job got easier to do, you're way more productive doing it. What's not to like? When you listen to the mathematicians, the answer is what we don't like is we actually enjoyed the process of doing proofs and that has been taken away.
And the same thing, I think just last week the FT had an article about musicians. A third of music uploaded to iTunes, I think it was, is now 100% AI generated. And it's not that composers don't like using technical tools to do their job.
They've done so for decades. But they actually enjoy the process of creating music. To take that away makes people unhappy.
So again, in terms of economics and social welfare or consumer welfare, these concepts in antitrust, all these innovations, they are great. They increase human welfare. But whether they also make people happier, that's a completely different page.
So that's why I think people should be a little more humble, not just as investors in what they know as they form their portfolios, but also to economists about whether their teachings should really apply to people's private lives as well, or whether they should just limit themselves to economics, which is what these tools were made for. It's not a new idea again. There was this guy called Adam Smith that we talked about earlier, wrote The Theory of Moral Sentiments in which he basically describes that people have this lack of compassion when looking at poor people.
The contrast to economic thinking couldn't be greater, where our welfare criteria usually just care about Pareto efficiency, but not about inequality, per se. So I think there's a lot of stuff in philosophy that economists for simplicity or convenience just brushed aside, but that are really necessary for us to understand the social challenges of our time, and hence also really what the right way of regulating the economy is.
Cameron Passmore: That response, Martin, might be the best ever set up for our traditional final question, which is, how do you define success in your life?
Martin Schmalz: Yeah, that was a tough one. I had to ask my partner. She didn't really know the answer either of how I defined success in my life.
There's a private dimension to it and a professional one. I think what both have in common is probably that I find it most meaningful to just create value for society and for others. I have expensive hobbies, so I don't mind if some of the value sticks with me as well, but for example, taking on the role of a regulator, the audit regulator that I spent two years serving as chief economist in.
You don't do that for the money, but you might do it because you think that you can improve disclosure by 0.1% and maybe reduce risk premium by a small fraction, but then do that with a gigantic amount of leverage that regulators. These rules we wrote, or the ones someone was tempted to write or we decided not to write, they affect 70 trillion dollars of equity market cap. Once you do a 0.1% times 70 trillion, that's still 70 billion. I just find it highly motivating to get out of bed in the morning when you think that you're contributing to such an amount of wealth creation for society or for the fundamentals of capitalism and all that good stuff. The same thing about being an economist. What I enjoy is thinking about providing economic thinking to make the world a better place in future generations.
This was a statement about focusing on the process, but also about creating that thing we call welfare economics.
Ben Felix: That's a great answer. This has been a great conversation, Martin. We really appreciate you coming on the podcast.
Cameron Passmore: Great to meet you. Thanks, Martin.
Martin Schmalz: Thank you very much for having me. It was a lot of fun.
Cameron Passmore: Ben, one of my sayings I say all the time is you have to think about the unintended consequences. So many things we've done over the years in business, it's been the unintended consequences that have dominated. This is something that we've talked about with guests in the past.
Ken French talked about the unintended returns, unexpected returns. And that's the part of this conversation I found so fascinating. Martin just asks these questions, like, huh, that's a really good question.
You think about each baker owning half of the bakery across the street and the unintended consequences of that, but that's effectively what's going on with the proliferation of index funds. Just so fascinating. It's interesting, it doesn't mean you change anything, but man, really cool and make you think.
Ben Felix: That's one of the important takeaways is that this stuff matters. That can be true while not having any implications for what index investors should actually do with their portfolios. There can be an aggregate market level effect that policymakers should be worried about, but I'm restating the tragedy of the commons.
It's fine for each individual to do this, but hey, we may have a problem developing here and increasingly. So as index funds get larger and larger, but who's going to step in and do something about that? I mean, should they, as Martin said during the conversation, we need to have a model of what may be going on for us to even have that conversation or even start thinking about that.
So I think he's contributed that in a couple of different ways in terms of common ownership and index funds more specifically.
Cameron Passmore: So many unanswered questions. It's going to be fascinating to see the research over the coming years and decades on this kind of stuff.
Ben Felix: And then the second part of the conversation, we're kind of talking about why don't wealthy people just index? That part's really interesting. He's teaching courses on this stuff.
He's talking to wealthy folks. You can tell he's been to some conferences. He's talking to family offices to get a feel for what's going on. And I thought his comments, they were fascinating.
Cameron Passmore: But it's the same pitch, no matter how many zeroes you have on your balance sheet.
Ben Felix: It's true.
Cameron Passmore: The pitch doesn't change.
Ben Felix: No, it does not change. And yeah, just what is smart doesn't really change.
Cameron Passmore: Markets work. That basic belief doesn't change depending on how many zeroes you have.
Ben Felix: Hard for people to accept though, especially, Martin talked about it. When you have someone who has been very successful, being concentrated, having control, having conviction, being active, making quick decisions, all that stuff. It's very hard to step back and shift your mindset to be a regular long-term passive investor when that's not how the wealth was created. I love that part of the conversation.
Cameron Passmore: Also the horizon-dependent risk aversion bungee jump example. That was really good.
Ben Felix: And how that relates to wealth management or at least asset management, delegated investment management as a sort of commitment device, like a pre-commitment to endure volatility in your portfolio makes the fee worthwhile because the counterfactual is that you just didn't take risk or didn't take as much risk. We know that's true. I mean, we've talked to lots of people who are in cash or in very conservative portfolios. And that's one of, not the only but one of, the reasons that they seek advice.
Cameron Passmore: I thought this was a great interview. I think the listeners loved it and if you listened this far we're very grateful for that. This is great stuff. Great guest.
Ben Felix: Super cool to talk to Martin and we appreciate everyone listening and we appreciate Martin coming on the podcast.
Cameron Passmore: You bet.
Disclaimer:
Portfolio management and brokerage services in Canada are offered exclusively by PWL Capital, Inc. (“PWL Capital”) which is regulated by the Canadian Investment Regulatory Organization (CIRO) and is a member of the Canadian Investor Protection Fund (CIPF). Investment advisory services in the United States of America are offered exclusively by OneDigital Investment Advisors LLC (“OneDigital”). OneDigital and PWL Capital are affiliated entities, and they mostly get on really well with each other. However, each company has financial responsibility for only its own products and services.
Nothing herein constitutes an offer or solicitation to buy or sell any security. Occasionally we tell you not to buy crappy investments in the first place, but that’s not the same thing as telling you to sell them.
This communication is distributed for informational purposes only; the information contained herein has been derived from sources believed to be “truthy,” but not necessarily accurate. We really do try, but we can’t make any guarantees. Even if nothing we say is fundamentally wrong, it might not be the whole story.
Furthermore, nothing herein should be construed as investment, tax or legal advice. Even though we call the podcast “your weekly reality check on sensible investing and financial decision making,” you should not rely on us when making actual decisions, only hypothetical ones.
Different types of investments and investment strategies have varying degrees of risk and are not suitable for all investors. You should consult with a professional adviser to see how the information contained herein may apply to your individual circumstances. It might not apply at all. Honestly, you can probably ignore most of it.
All market indices discussed are unmanaged, do not incur management fees, and cannot be invested in directly. Which is a shame, because it would be awesome if you could.
All investing involves risk of loss: including loss of money, loss of sleep, loss of hair, and loss of reputation. Nothing herein should be construed as a guarantee of any specific outcome or profit.
Past performance is not indicative of or a guarantee of future results. If it were, it would be much easier to be a Leafs fan.
All statements and opinions presented herein are those of the individual hosts and/or guests, are current only as of this communication’s original publication date. No one should be surprised if they have all since recanted. Neither OneDigital nor PWL Capital has any obligation to provide revised statements and/or opinions in the event of changed circumstances.
Is there an error in the transcript? Let us know! Email us at info@rationalreminder.ca.
Be sure to add the episode number for reference.
Participate in our Community Discussion about this Episode:
https://community.rationalreminder.ca/t/the-winners-and-losers-of-index-investing/43714
Sources From Today’s Episode:
https://zbib.org/a79d2e68294b4263a796d83123543200
Links From Today’s Episode:
Stay Safe From Scams — https://pwlcapital.com/stay-safe-online/
Rational Reminder on Apple Podcasts — https://itunes.apple.com/ca/podcast/the-rational-reminder-podcast/id1426530582.
Rational Reminder on Spotify —https://open.spotify.com/show/6RHWTH9iW7hdnA7eAg7ukO?si=fe7f60349b584026
Rational Reminder on Instagram — https://www.instagram.com/rationalreminder/
Rational Reminder on YouTube — https://www.youtube.com/channel/
Benjamin Felix — https://pwlcapital.com/our-team/
Benjamin on X — https://x.com/benjaminfelix
Benjamin on LinkedIn — https://www.linkedin.com/in/benjaminwfelix/
Martin on LinkedIn — Martin Schmalz - Global Corporate Governance Colloquia | LinkedIn
Martin on X (for antitrust-related posts) — Martin Schmalz (@martincschmalz) / X
Martin’s website — MartinCSchmalz